Mains Ready By December. Smash Mains & Smash PYQ Admissions Open

Type: Op-ed

  • Smart glasses highlight gaps in privacy laws

    Why in the News

    Meta’s smart glasses, which can discreetly record video and audio of anyone around the wearer, have renewed concerns over surveillance and consent, and over how far the Digital Personal Data Protection Act, 2023 actually protects a bystander who never agreed to be recorded. The Supreme Court’s nine-judge Bench in Justice K.S. Puttaswamy v. Union of India (2017) held privacy to be a fundamental right intrinsic to Article 21, developing a three-part legality-necessity-proportionality test for any restriction on it. Wearable recording devices normalised for everyday use test that framework in a setting the 2017 judgment did not anticipate: a bystander with no relationship to the device’s owner, and no practical way to know they are being recorded.

    Why do smart glasses expose a specific gap in India’s privacy framework?

    1. The Digital Personal Data Protection Act, 2023 is built around consent, which a bystander cannot give: The Act’s core protection mechanism requires a data principal’s consent before personal data is processed, a structure that assumes a data subject who is a party to the transaction, not a bystander recorded without their knowledge by someone else’s device.
    2. No dedicated framework for covert or discreet recording devices: Existing privacy protections address data processing by an identifiable data fiduciary, typically a company or platform, not the diffuse, device-level recording enabled by consumer wearables carried by private individuals.
    3. Enforcement depends on the bystander detecting the recording: Because smart glasses are designed to record discreetly, a bystander has no practical way to exercise any of the rights the 2023 Act grants a data principal, since exercising those rights first requires knowing that one’s data was processed at all.
    4. Cybercrime figures already show a rising surveillance-adjacent harm pattern: National Crime Records Bureau data has recorded a rising trend in cybercrime cases involving unauthorised recording and image-based harassment, a pattern smart-glasses-style wearables are positioned to accelerate.

    Conclusion

    Smart glasses expose a structural gap between a consent-based data protection framework and a recording technology that operates on people who never consented to anything. Closing that gap requires provisions specific to covert or ambient recording devices, rather than relying on the same consent architecture built for data fiduciaries processing information from their own users.

    What is the Right to Privacy, and what does it protect?

    1. About: The Right to Privacy is a fundamental right, read into Article 21’s guarantee of life and personal liberty, protecting an individual’s control over personal information, bodily integrity, and personal decisions from unjustified interference by the State.
    2. Rationale: The right exists because personal autonomy, from choice of partner to control over one’s own data trail, is treated as intrinsic to human dignity rather than a privilege the State may withdraw.
    3. Named typology: The Supreme Court in Puttaswamy (2017) recognised several strands within the right: informational privacy over personal data, decisional autonomy over intimate personal choices, bodily integrity against intrusive procedures, and digital privacy against online surveillance.
    4. Proportionality test for restrictions: Any state action restricting privacy must meet a three-part test: legality (backed by law), a legitimate aim, and proportionality between the means used and the aim pursued.
    5. Institutional gap in independent oversight: Agencies such as the Intelligence Bureau, the Research and Analysis Wing, and the National Investigation Agency operate without a dedicated, independent body reviewing their surveillance activity for privacy compliance.
    6. Colonial-era laws still authorise interception: Provisions in the Telegraph Act continue to authorise phone tapping under standards that predate the Puttaswamy proportionality test, creating a mismatch between old authorisation powers and the newer constitutional standard.
    7. Corporate data harvesting outside individual awareness: Technology platforms collect and monetise personal data at a scale most users do not track or understand, a form of privacy erosion the Digital Personal Data Protection Act, 2023 only partially addresses through its consent and purpose-limitation provisions.
    8. Low digital literacy limits the exercise of privacy rights: Citizens frequently do not know what data they have given consent to share, or how to invoke the correction and erasure rights the 2023 Act grants them.

    Challenges in protecting the right to privacy

    1. Mass surveillance without independent judicial oversight: Interception and surveillance decisions in India are authorised through executive processes rather than prior judicial warrant. Eg. Allegations around the use of Pegasus spyware against journalists and activists in 2021 raised exactly this oversight gap. Fix. Introduce a judicial or quasi-judicial warrant requirement before any interception order takes effect, replacing the current executive-only authorisation.
    2. National-security exemptions in the 2023 Act draw criticism: The Digital Personal Data Protection Act, 2023 permits government agencies to be exempted from several of its obligations on national security and public-order grounds. Eg. Government bodies notified under the Act’s exemption provisions are not bound by the same data-minimisation and purpose-limitation duties private data fiduciaries face. Fix. Require any national-security exemption to be time-bound and reviewed periodically by an independent oversight body rather than granted as a standing exemption.
    3. Corporate surveillance through data-driven advertising: Large technology platforms build detailed behavioural profiles from data users hand over without meaningfully understanding the trade-off. Eg. Targeted political and commercial advertising built on granular user profiling has drawn regulatory scrutiny in multiple jurisdictions. Fix. Mandate clear, layered consent disclosures under the 2023 Act’s rules that separate necessary data use from optional profiling-based use.
    4. Health data retention concerns from pandemic-era tools: Contact-tracing and health applications built during the COVID-19 pandemic raised unresolved questions about how long the government retains the health data those apps collected. Eg. Aarogya Setu’s data retention and sharing practices drew sustained criticism from privacy researchers. Fix. Set a statutory data-retention ceiling for any health-emergency application, with automatic deletion once the stated public-health purpose ends.
    5. No dedicated authority solely focused on privacy enforcement: The Data Protection Board established under the 2023 Act adjudicates complaints but does not function as a proactive privacy regulator auditing surveillance practices across government and industry. Fix. Expand the Data Protection Board’s mandate to include periodic, unprompted audits of large-scale surveillance and data-processing systems, government and private alike.

    Back2Basics: Digital Personal Data Protection Act, 2023

    1. India’s first standalone law on personal data processing, built around consent as the primary legal basis for processing, with defined exceptions for legitimate uses such as employment and government functions.
    2. Creates the Data Protection Board of India as the adjudicatory body for data-protection complaints and penalties.
    3. Grants data principals rights to access, correct, and erase their personal data, and imposes purpose-limitation and data-minimisation duties on data fiduciaries.
    4. Permits the government to exempt specified agencies from several of the Act’s obligations on national security and public-order grounds, a provision that has drawn criticism for its breadth.

    Matching Previous Year Question

    “[2024, GS3, 10 marks] Describe the context and salient features of the Digital Personal Data Protection Act, 2023”
  • The fact is youth unemployment has a household cost

    Why in the News

    Periodic Labour Force Survey (PLFS) 2025 data records youth unemployment at 14.8 percent and a Not in Employment, Education or Training (NEET) rate of 40.1 percent among the tertiary-educated, and the argument advanced from this data is that graduate joblessness is a household-level economic cost, not only an individual setback. A young person’s inability to find work does not only reduce that person’s own income, it removes an income the household had budgeted around, often after the household had itself financed the degree that produced no job.

    What is the household cost, distinct from the individual one?

    1. Sunk cost of financing the degree: Households that borrow or spend savings to fund a graduate’s education absorb that cost with no return if the graduate cannot find matching work, a loss the individual unemployment rate does not price in.
    2. Deferred contribution to household income: A household budgets around the expectation that an educated young adult will begin contributing income at a certain age; unemployment past that age forces the household to keep supporting a wage-earner it had expected to become a net contributor.
    3. Compounding effect on savings for other dependants: Money a household would have redirected toward a younger sibling’s education, a parent’s healthcare, or retirement savings instead continues to support an unemployed graduate.
    4. Psychological and bargaining costs within the household: Prolonged dependence on parents past the expected age of self-sufficiency affects a young adult’s standing and decision-making power within the household, a dimension PLFS-style employment data cannot itself measure but that the 40.1 percent NEET rate among the tertiary-educated makes newly visible.

    How does the tertiary-educated NEET rate compare with the general NEET pattern?

    1. Tertiary-educated NEET rate far exceeds the general rate: At 40.1 percent, the NEET rate among India’s tertiary-educated youth is markedly higher than the NEET rate among youth without a degree, inverting the usual expectation that more education reduces the risk of disengagement from work.
    2. Concentration in urban, aspirational households: The households most likely to have financed a tertiary degree, and to therefore carry the sunk cost described above, are disproportionately urban and lower-middle income, the segment for whom a graduate’s income was budgeted as a route out of that bracket.

    Conclusion

    Youth unemployment at 14.8 percent and a 40.1 percent NEET rate among the tertiary-educated do not describe an individual labour market outcome alone. They describe a household that financed an investment in education and is not yet receiving the income return it planned around, a cost that persists in household budgets even where it does not appear in an individual’s own unemployment statistic.

    Youth unemployment in India

    1. About: Youth unemployment measures joblessness among the working-age population, typically 15 to 29 years, whose job search outcomes diverge sharply from the adult labour force.
    2. Rationale for tracking it separately: Youth unemployment behaves differently from the aggregate rate because young workers are more likely to be first-time job seekers with no accumulated informal-sector fallback, so a downturn hits them earliest and hardest.
    3. Recognised typology: Unemployment among India’s youth spans frictional joblessness during the transition from education to work, structural joblessness from a skills mismatch, and disguised underemployment in low-productivity family enterprises and agriculture.
    4. Jobless growth in services: Services drive the largest share of GDP growth but employ under 30 percent of the workforce, limiting the sector’s capacity to absorb new entrants.
    5. Skill deficit at graduation: Only about half of India’s graduates are assessed as readily employable, per employability surveys, pointing to a curriculum gap rather than a shortage of degree holders.
    6. Weak manufacturing absorption: Manufacturing contributes only 16 to 18 percent of GDP, well below the roughly 26 percent contribution in China, limiting the formal, labour-intensive job creation India’s youth bulge needs.
    7. Informality as the default outcome: Over 90 percent of India’s workforce remains informal, so even youth who do find work often find it without security, benefits, or a written contract.
    8. Female youth workforce deficit: Caregiving duties, domestic responsibilities, and mobility constraints keep young women out of paid employment at a much higher rate than young men.

    Challenges in addressing youth unemployment

    1. Survey methodology undercounts informal and gig work: PLFS-style surveys do not fully capture home-based, gig, or platform work within India’s overwhelmingly informal workforce. Eg. Platform-based delivery and ride-hailing work is not consistently classified in the survey’s job categories. Fix. Update survey instruments to explicitly capture gig, platform, and digital work categories, aligned with International Labour Organization and System of National Accounts definitions.
    2. Low-frequency rural data delays policy response: Rural employment data has historically been measured only annually, compared with quarterly urban estimates, masking rural distress in real time. Eg. A poor monsoon’s effect on rural non-farm employment often does not show up in national data until the following year’s release. Fix. Extend the quarterly PLFS survey design to rural areas at the same frequency as urban areas.
    3. Capital-intensive investment bias: Investment continues to flow toward capital-intensive sectors such as information technology and infrastructure rather than the labour-intensive sectors that absorb semi-skilled youth. Eg. Automation in manufacturing has reduced the labour intensity of new capacity even as output has grown. Fix. Direct production-linked incentives toward labour-intensive sectors such as textiles, leather, and food processing, alongside the existing electronics-focused schemes.
    4. Demographic dividend at risk of becoming a demographic trap: A youth bulge that cannot find work stops being an economic asset and starts becoming a fiscal and social liability as the cohort ages without having built savings or skills. Eg. State of Working India 2026 estimates 9.2 crore youth in the NEET category nationally. Fix. Expand the government’s employment-linked incentive schemes and apprenticeship mandates specifically targeted at the 21 to 29 age cohort.
    5. Weak coordination across employment data systems: Employees’ Provident Fund Organisation payroll data, the National Career Service portal, and PLFS survey data are not integrated, making it hard to track whether a given policy intervention is actually creating net new jobs. Eg. The Employment Linked Incentive scheme announced in 2025 tracks payroll additions but not whether they represent new jobs or reclassified existing ones. Fix. Build a single integrated employment data dashboard drawing on EPFO, NCS and PLFS data for real-time tracking.

    Back2Basics: NEET (Not in Employment, Education or Training)

    1. An internationally used labour-market indicator that counts young people who are neither working, studying, nor undergoing any training, distinct from the unemployment rate, which only counts those actively seeking work.
    2. Captures discouraged job seekers and those who have withdrawn from the labour force entirely, a population the standard unemployment rate does not measure.
    3. The State of Working India 2026 report estimates roughly 9.2 crore Indian youth in this category.

    Matching Previous Year Question

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • [24th August 2026] The Hindu OpED: Core concerns

    [24th August 2026] The Hindu OpED: Core concerns

    Question (2017, GS3): ““Industrial growth rate has lagged behind in the overall growth of Gross-Domestic-Product (GDP) in the post-reform period” Give reasons. How far the recent changes is Industrial Policy are capable of increasing the industrial growth rate?
    Linkage: The easing of the Manufacturing PMI to its lowest level since August 2021 due to weak domestic demand is a classic real-time symptom of industrial growth lagging behind overall economic expansion. It forces candidates to examine why Indian manufacturing struggles to maintain sustained momentum.

    Mentor Comment

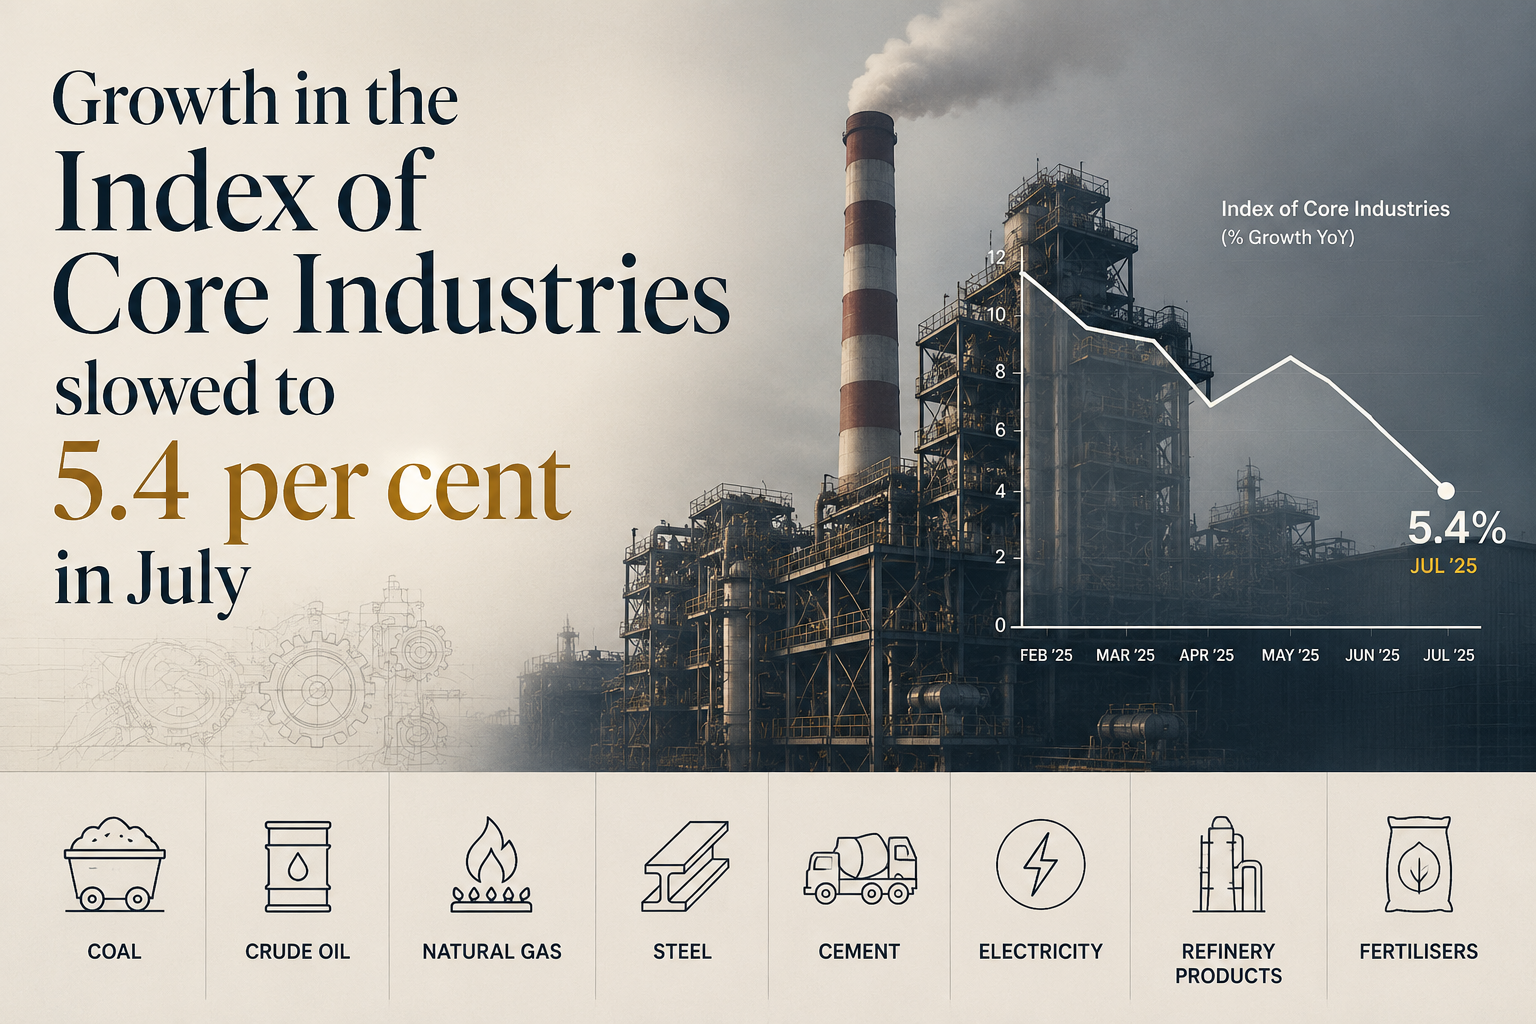
    Growth in the Index of Core Industries slowed to 5.4 per cent in July from 6 per cent in the previous month. The Manufacturing Purchasing Managers’ Index eased in the same month to its lowest level since August 2021, on weak domestic demand conditions. July’s core sector growth was still the second highest rate in the last seven months. The tension sits between that headline and its composition: a large part of the growth rests on a statistical low base effect, the two genuinely strong sectors are cement and electricity, and the domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months.

    What is the Index of Core Industries?

    • What it measures: The Index of Core Industries measures the combined production of the country’s core infrastructure industries, covering coal, crude oil, natural gas, refinery products, fertilisers, steel, cement and electricity.
    • Why it is watched: These industries carried a combined weight of about 40 per cent in the Index of Industrial Production, so the core index acts as an early read on industrial output before the fuller index is released.
    • Current series: The index is compiled on a revised new series, for which comparable data currently extends back only about 14 months.

    Why is the July core sector number weaker than it looks?

    • Growth rests on a low base: A large part of even this slower growth is based on a statistical low base effect, where a contraction in the corresponding month of the previous year makes the current month’s output look like expansion.
    • Coal illustrates the effect: The coal sector grew at an 11 month high of 7.6 per cent in July. That was measured against a contraction of 12.3 per cent in July of last year.
    • Refinery products repeat the pattern: The refinery products sector snapped a three month streak of contraction to grow at 2.7 per cent. This too was measured against a contraction in July 2025.
    • Iron ore’s strength is partly base driven: The iron ore sector grew at 29.5 per cent, slower than 44.5 per cent in June. Its comparison base is contractions of 16.4 per cent in June and 7.1 per cent in July of last year.
    • The headline flatters the trend: A rate that is second highest in seven months coexists with an easing demand signal, which means the ranking of the number matters less than what produced it.

    Which sectors are carrying the index and which are dragging it?

    • Steel has slowed sharply: The steel sector decelerated to 2.9 per cent in July from 5.6 per cent in June and 15.7 per cent in July of last year. This is a genuine slowdown rather than a base effect.
    • Hydrocarbons are a standing drag: The domestic crude oil and natural gas sectors have contracted continuously for at least the last 14 months for which the new series has data.
    • Electricity remains strong but is decelerating: The electricity sector grew at 9 per cent in July. That was slower than two consecutive months of double digit growth in May and June, which were lifted by prevalent heatwave conditions in many parts of the country.
    • Cement accelerated: The cement sector sped up to 13.1 per cent, the clearest genuine acceleration in the index.
    • The bright spots are only two: Within the core index, cement and electricity were the only two sectors reading as bright spots, and such positive trends were few and far between.

    Does the core sector number describe output or demand?

    • The two indicators point in opposite directions: The core index recorded its second highest growth in seven months in the same month that the Manufacturing Purchasing Managers’ Index fell to its lowest since August 2021.
    • They measure different things: The core index counts physical production in a set of infrastructure industries. The Manufacturing Purchasing Managers’ Index records what purchasing managers report about new orders and demand conditions.
    • A base effect can mask a contraction: A sector recovering from a deep fall registers a high growth rate at a low level of output, so a rate can rise even as demand conditions ease.
    • Weather and construction are not demand: The strongest readings came from electricity, lifted by heatwave conditions, and from cement, which tracks construction activity rather than broad consumer demand.
    • The forward reading is slack: Easing demand conditions were already being predicted by other indicators before the core sector data appeared, so the July slowdown was not a surprise.

    How is energy import dependence turning into a cost shock?

    • Import volumes are rising: India’s crude oil imports rose 13.3 per cent in volume terms in July. Liquefied Natural Gas (LNG) imports grew a more marginal 1.5 per cent.
    • Domestic supply is not filling the gap: Against the falling domestic base noted above, the economy’s appetite is being met from abroad rather than from home production.
    • The bill has jumped: High oil prices meant the crude oil import bill jumped 41 per cent in July, so a 13.3 per cent volume rise translated into a far larger payment outgo.
    • A tariff shock is queued behind it: The 100 per cent tariffs the United States is preparing to levy on countries such as India that import Russian oil will once again burden Indian exporters.
    • Blending has not yet displaced imports: Moving to 20 per cent ethanol blending has not yet impacted oil imports materially, so the substitution effect is not visible in the July numbers.

    Challenges to the Index of Core Industries as a growth signal

    • Base effects distort the headline rate: A contraction in the year ago month converts a modest recovery into a high growth print, which misleads on the level of output. Eg. Coal’s 11 month high of 7.6 per cent in July sat on a 12.3 per cent contraction in July of the previous year. Fix. Publish index levels and two year compound rates alongside the year on year rate in every release.
    • Coverage is narrow: The index tracks a small set of infrastructure industries and therefore misses most of the economy’s output. Eg. Services contribute over half of Gross Value Added and are entirely outside the core index. Fix. Publish the core index alongside a high frequency services activity indicator so the composite reading is visible.
    • Weights favour public sector heavy industries: The largest weights sit in sectors dominated by public enterprises and administered pricing, so the index responds to policy decisions as much as to market demand. Eg. Refinery products and electricity output move with administered allocation and tariff decisions. Fix. Rebase and reweight the index on a fixed cycle with published sensitivity of the headline to each sector’s weight.
    • Informal and small firm output is invisible: Production by micro and small enterprises is not captured, so a squeeze concentrated there does not register. Eg. Of about 64 million micro, small and medium enterprises, only around 14 per cent have access to formal credit and most stay outside statistical registers. Fix. Link the index to Goods and Services Tax e-way bill and electronic invoice data to capture small firm activity.
    • Provisional data is heavily revised: Early estimates are released on partial returns and are revised in later months, so a policy read taken on the first print can reverse. Eg. Iron ore’s July reading of 29.5 per cent followed a June figure of 44.5 per cent, a swing large enough to change the quarterly picture on revision. Fix. Publish a standing revision history for each sector so the reliability of the first print is visible.
    • It reads supply, not demand: The index counts what was produced, not what was bought, so it can rise while orders fall. Eg. July’s core growth of 5.4 per cent coincided with the Manufacturing Purchasing Managers’ Index at its weakest since August 2021. Fix. Present the core index and the demand side survey indicators in a single monthly dashboard rather than as separate releases.

    Conclusion

    The Indian economy looks set for a period of slack demand, higher costs and moderating growth. The July core sector reading does not contradict that: a large part of its growth is base driven, only cement and electricity grew genuinely strongly, and the sectoral spread set out above is narrow. The cost side is worsening independently, on the import bill and the tariff exposure already recorded. Whether the next few months show a genuine industrial recovery depends on domestic demand rather than on the base against which growth is measured.

    Industrial Growth in India

    • Manufacturing’s share is stuck: Manufacturing contributes around 17 per cent of Gross Domestic Product (GDP), far below the 25 per cent target set under Make in India.
    • Global standing: India holds about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent, with domestic manufacturing output nearing $1 trillion in 2025-26.
    • Concentration: Maharashtra, Gujarat and Tamil Nadu account for about 40 per cent of net value added in manufacturing, and half the States have no operational Special Economic Zone.

    Government Initiatives for Industrial Growth

    • National Manufacturing Mission: Announced in the 2025-26 Budget, it unifies manufacturing policy and targets a 25 per cent GDP share with 143 million jobs by 2035.
    • Production Linked Incentive Scheme: Covers 14 sunrise and strategic sectors with outcome linked incentives, drawing over ₹1.76 lakh crore in committed investment as of March 2025.
    • Semiconductor Mission: A ₹76,000 crore framework under which 10 projects worth about ₹1.60 lakh crore have been approved.
    • Industrial Corridors Programme: India approved 11 corridors covering 32 projects, with 12 new industrial nodes cleared in 2024 for plug and play industrial cities.

    Challenges in Industrial Growth

    • Compliance load falls on small firms: Micro, small and medium enterprises face over 1,450 annual compliances, which consumes management time that would otherwise go into expansion. Eg. Annual compliance costs for such firms run to ₹13 lakh to ₹17 lakh. Fix. Adopt third party certification in place of repeat inspections, as the Ajay Shankar Committee recommended.
    • Regional concentration leaves capacity idle: Industrial value added clusters in three States, so national incentives do not translate into national capacity. Eg. Half of India’s States have no operational Special Economic Zone. Fix. Weight central incentive disbursal toward States below the national share of net value added.
    • Technology transition is slow in strategic segments: Domestic capability lags in electronics, semiconductors and renewable energy components, which keeps high value assembly abroad. Eg. India remains heavily dependent on imports for semiconductors and advanced electronic components. Fix. Extend Production Linked Incentives to upstream segments such as advanced materials and green hydrogen rather than final assembly alone.
    • Credit does not reach small manufacturers: Formal finance is unavailable to the great majority of small firms, so they cannot fund the fixed capital that raises productivity. Eg. The unmet credit demand of the micro, small and medium enterprise sector is estimated at about ₹20 lakh crore to ₹25 lakh crore. Fix. Expand cash flow based lending against Goods and Services Tax returns rather than collateral based assessment.
    • Trade barriers raise export uncertainty: Tariff action by large markets can remove the price advantage of an entire export segment without notice. Eg. The United States imposed a 50 per cent tariff in August 2025, hitting about 55 per cent of India’s exports to that market. Fix. Deepen global value chain participation through trade agreements and diversify destination markets under a China plus one strategy.
  • Measuring manufacturing growth afresh: Three questions

    Why in the News

    The new Gross Domestic Product (GDP) series of the Ministry of Statistics and Programme Implementation (MoSPI) shows the manufacturing Gross Value Added (GVA) deflator recording negative growth for nine consecutive quarters between 2023 and 2025. The same series places the level of real manufacturing GVA in 2025-26 at no less than 15 percentage points above the Index of Industrial Production (IIP) for manufacturing. When the new series was announced, the Chief Economic Advisor and the Secretary, MoSPI stated that the estimates rested on a new methodology. That methodology was said to have solved the measurement problems that had bedevilled the old series, including in manufacturing. MoSPI has not yet released the detailed standard document explaining the new calculations. Three specific anomalies in the manufacturing numbers therefore cannot be tested against the stated method, and the plausibility of the series has to be assessed from the numbers themselves.

    What is the manufacturing Gross Value Added deflator?

    1. Gross Value Added, defined: GVA for a sector is the value of its output minus the value of its intermediate inputs. It measures what producers in that sector actually added, before taxes on products are added and subsidies subtracted.
    2. What the deflator does: The sector deflator is the price index that converts nominal GVA at current prices into real GVA at base year prices. Real GVA equals nominal GVA divided by that deflator.
    3. What its movement signals: A deflator growing negatively means the sector’s own price level is falling. Real growth then runs ahead of nominal growth by the size of that fall.

    Why does confidence in manufacturing data matter now?

    1. The China Squeeze: The Chinese manufacturing export machine has again moved across world markets and threatens lower-skill manufacturing in poorer countries. The pressure this creates on Indian producers is what the data is being asked to measure.
    2. Two decades of stated ambition: The Union government set major ambitions for the sector, beginning with the flagship Make in India programme in 2014. The production-linked incentive (PLI) scheme followed several years later.
    3. The PLI’s dual purpose: The scheme was in part a response to the opportunities opened by the China-plus-one shift in global sourcing. It was also a response to the challenge of aggressive Chinese competition.
    4. Conflicting signals elsewhere: The wider economy is sending contradictory signals at present. Understanding manufacturing performance is the route to lifting some of that confusion.
    5. A recognised prior problem: Problems in manufacturing sector data under the previous series were widely recognised. MoSPI made strenuous efforts to address them in the new series.

    Why has the manufacturing deflator shown falling prices for nine straight quarters?

    1. The anomaly itself: The manufacturing GVA deflator records negative growth, meaning falling price levels, for nine consecutive quarters between 2023 and 2025. No comparable stretch of deflation appears anywhere else in the price data for that period.
    2. The core inflation test: The core Consumer Price Index (CPI), which excludes food and energy-related products, shows no sign of deflation across those quarters. Core CPI through December 2025 rests on the 2011-12 series and the March 2026 reading on the 2024 series.
    3. The wholesale price defence, and its limit: The wholesale price index (WPI) was negative for some of this period. It was not negative for nine consecutive quarters.
    4. Why WPI is the wrong benchmark anyway: The GVA deflator should not move in line with the WPI. The WPI is overly driven by input prices, and a value added deflator must reflect output prices net of inputs.

    Why is real GVA growth almost twice IIP growth?

    1. The size of the gap: In 2025-26 the level of real manufacturing GVA exceeded the IIP by no less than 15 percentage points. Both series are measured on the 2022-23 base.
    2. The growth gap it implies: Annual average real growth of manufacturing between 2022-23 and 2025-26 measured by GVA is about twice that measured by the IIP. The two figures are about 11 per cent against about 6 per cent.
    3. The informal sector explanation, and why it fails: Real GVA includes the informal sector and the IIP excludes it, so faster informal growth could in principle open a gap. For the most recent two years informal sector performance has been proxied by formal sector data, which makes the explanation mechanically impossible.
    4. The volumes versus value added explanation: The IIP measures output volumes rather than value added. A widely held perception holds that real GVA can grow faster than real output when input prices fall.
    5. Why that perception is wrong: Real GVA is calculated at constant prices, not at changing prices, so falling input prices cannot lift it. Real value added can grow faster than output volumes only where productivity improves, that is where firms become more efficient in using intermediate inputs.

    Why has the link between the two series broken down?

    1. The pre-2011 benchmark: Before the 2011-12 methodology changes, GVA and IIP moved closely together. The correlation between their growth rates over June 2005 to that break was 0.8.
    2. The post-2011 divergence: The two series diverged after the 2011-12 methodology changes. That divergence has been exacerbated in the new series rather than corrected by it.
    3. The recent segment: Since September 2022 the two series move very differently. The comparison excludes the Covid quarters from June 2020 to March 2022.
    4. The character of the difference: The real GVA series bounces around a great deal across quarters. The IIP series over the same stretch is fairly stable.

    What do the three questions together say about the new series?

    1. None is individually decisive: No one of the three issues is dispositive about the quality of the new series. Each is an unexplained pattern rather than a demonstrated error.
    2. The missing document is the binding constraint: The detailed standard document explaining the new calculations has not been released. Independent researchers therefore cannot check the anomalies against the method that produced them.
    3. The methodology claim raises the bar, it does not lower it: The new series was presented as the fix for exactly the manufacturing measurement problems of the old series. Anomalies concentrated in manufacturing are the hardest place for that claim to sit unexplained.
    4. What plausible explanations would buy: Explanations would engender confidence in the new GDP figures. They would also allow an assessment of the state of Indian manufacturing and of the impact of recent government actions to revive it.

    Challenges to the new GDP series’ manufacturing estimates

    1. Deflator choice drives the real number: Real GDP requires choosing a deflator, and the production side deflator is heavily influenced by the WPI. Eg. In FY23 a global commodity price surge pushed the WPI into double digits, and the high deflator suppressed measured real growth. Fix. Complete the WPI base revision so the deflator basket reflects the current price structure.
    2. No producer price index exists: India deflates goods sectors with a wholesale index built for trade flows rather than for producer output. Eg. Services sectors are deflated using CPI components because no dedicated producer price series covers them. Fix. Introduce a Producer Price Index on the model used across advanced statistical systems and retire WPI-based deflation.
    3. Transparency lags the release: The estimates reach the public well before the sources and methods behind them. Eg. The new series arrived with a stated methodology claim and without the standard explanatory document. Fix. Publish the sources and methods volume alongside the series so verification is concurrent with release.
    4. Informal output is still partly extrapolated: Informal sector performance for recent years is proxied from formal sector data, which cannot capture divergence between the two. Eg. The old series extrapolated large-company filings to the whole informal economy and stayed blind to the sharper hit small firms took after demonetisation. Fix. Shorten the lag on the Annual Survey of Unincorporated Sector Enterprises so proxying is not required for two full years.
    5. Statistical independence has been questioned: Resignations from the National Statistical Commission and withheld survey results have raised concerns about the autonomy of official statistics. Eg. Two members of the Commission resigned in 2019 over the handling of employment data. Fix. Constitute an independent statistical commission with a statutory mandate, as recommended by the Rangarajan Commission in 2001.

    Conclusion

    The new GDP series was presented as the answer to the manufacturing measurement problems of the old one, and its manufacturing numbers now carry three patterns that the stated methodology does not obviously produce. A deflator falling for nine quarters, a 15 percentage point level gap against the IIP and a correlation that has weakened since 2005-2012 are each testable claims that cannot be tested without the sources and methods document. Releasing that document is the precondition for confidence in the figures. Whether and how Indian manufacturing has stood up to Chinese competition is a question only reliable data can answer.

    “[2021, GS3, 10 marks] Explain the difference between computing methodology of India’s Gross Domestic Product(GDP) before the year 2015 and after the year 2015.”

  • Investment question has a political answer

    Why in the News

    Private corporate investment in India remains considerably lower than the peak seen in the mid 2000s, even as large corporates hold substantial cash. Firms are deploying funds in financial assets rather than building physical assets such as factories, and are taking money out of the country rather than investing it here. The standard explanations offered for this are subdued domestic demand and global uncertainty. A political economy explanation is now advanced instead, locating the cause in how political power structures affect investment decisions. Centralisation of political power has been unmistakable after 2014, accompanied by fiscal centralisation and a reconfiguration of federal structures. The contested claim is that market concentration around a handful of “national champions” is not an accident of policy but is politically useful, which would make an investment revival costly to the current political settlement.

    What are “national champions”?

    1. Definition: A national champion is a large domestic business group that a government treats as the preferred vehicle for building strategic capacity, and that is favoured in policy design as a result.
    2. How the status is conferred: Preference operates through the terms of auctions, tariffs, incentive eligibility, clearances and access to public contracts rather than through an announced designation.
    3. The economic consequence: A handful of such groups now command far greater sway over the economy than before, which raises the entry barrier facing any firm attempting to compete with them.

    What does the investment slowdown actually look like?

    1. Cash-rich firms are not building: Large corporates hold funds but are not committing them to new capacity in India.
    2. Capital is leaving: Companies are taking money out of the country rather than investing it domestically.
    3. Investment is below its own peak: Private corporate investment remains considerably lower than the level reached in the mid 2000s.
    4. Financial assets over physical assets: Corporate India is more keen to deploy funds in financial assets than to use them for factories and plant.
    5. The standard explanations are incomplete: Subdued domestic demand and global uncertainty have been put forward, and neither accounts for why firms with the means to invest choose not to.

    Why does the concentration of political and market power deter private investment?

    1. Political and fiscal centralisation: Centralisation of political power after 2014 has been accompanied by greater fiscal centralisation and a reconfiguration of federal structures, including attempts to restrict the powers of states and, as a consequence, of regional parties. Eg. The Mines and Minerals (Development and Regulation) Amendment Act, 2026, amending the 1957 law under which the State owns the mineral and signs the lease while the Centre sets the rules and the royalty rate.
    2. Market concentration has moved in step: The rise of a handful of large companies, aided by policy, has given them far greater sway over the economy than ever before.
    3. One, patronage for smaller firms has dried up: The concentration of political power and the decline in the relative power of regional parties has ended the patronage and protection that were afforded to smaller and regional firms, who could rise up and become national players.
    4. Two, policy uncertainty and an uneven playing field: Higher barriers to entry and terms tilted towards larger corporates make it harder for new players to emerge, and firms will not invest if they fear the rules of the game can be arbitrarily changed or that they can be caught on the wrong side of policies. Policy credibility is what is at stake.
    5. Three, the fear of being muscled out: Investors fear that business success will be met by a hostile takeover by a national champion, so the question is not whether they are allowed to operate but whether they can stay in business and remain competitive over the next 10 to 20 years.

    Why would dispersing economic power be politically costly?

    1. Competition requires a rethink of the strategy: For the larger corporate sector to ramp up investment and for competition to emerge, the strategy of relying on a few national champions needs to be reconsidered.
    2. Dispersed economic power funds political opposition: A larger number of big private players would disperse rather than concentrate economic power, which would in turn increase the funding avenues available to Opposition parties.
    3. Economic competition feeds political competition: Weakening the concentration of economic power would possibly weaken the concentration of political power, so greater economic competition could lead to greater political competition.
    4. The two open questions: It is unsettled whether the current political structure creates the space for new players to safely invest and emerge as competitors to the national champions, or whether market concentration is itself politically useful.

    Why do the ingredients of an investment boom not produce one?

    1. The macroeconomic conditions are present: An undervalued exchange rate, depressed real wages and sustained public sector investment in infrastructure are all in place, alongside the demographic dividend.
    2. The same mix powered East Asia: This combination powered the rise of countries such as China and South Korea, where firms responded to it with large capacity additions.
    3. India’s firms are not responding: Firms are likely to remain hesitant and unsure about investing without a change in the approach, despite those conditions.
    4. Confidence, not capability, is binding: Investment decisions are taken only when investors think they have a fair chance of benefiting from them.
    5. The end state if nothing changes: The consequent absence of competition raises the possibility of an uncompetitive, high-cost economy.

    Challenges to the national champions strategy

    1. Concentration raises consumer and input costs: Dominant firms in a sector face little pressure to hold prices down, which raises costs for every downstream user. Eg. Telecom tariffs rose sharply after the sector consolidated into three private operators. Fix. Use the deal value threshold introduced by the Competition (Amendment) Act, 2023 to review acquisitions that current turnover tests miss.
    2. Policy-created advantage is hard to withdraw: Once a group builds capacity on the strength of an incentive, removing the incentive becomes a shock the government is reluctant to deliver. Eg. Most approved incentive under the Production Linked Incentive scheme for large-scale electronics manufacturing has flowed to a small group of mobile phone assemblers. Fix. Publish sunset dates and firm-level disbursement data with each incentive scheme so withdrawal is scheduled rather than negotiated.
    3. Concentrated bank exposure transmits firm risk to the system: Lending concentrated in a few large groups converts a single group’s distress into a banking problem. Eg. The corporate loan losses that produced the non-performing asset build-up of the 2010s were concentrated in a handful of infrastructure and metals groups. Fix. Enforce large exposure limits at group rather than borrower level and publish group-wise banking exposure.
    4. Bidding rules can favour incumbents: Net worth, prior experience and bank guarantee conditions in auctions and tenders can exclude new entrants before price is considered. Eg. Critical mineral block auctions have repeatedly failed for want of qualified bidders. Fix. Set qualification thresholds proportionate to block or contract size and allow consortium bidding for first-time entrants.
    5. Competition enforcement is slow relative to market speed: Investigations concluded years after conduct occurs cannot restore a market that has already tipped. Eg. Appeals against Competition Commission of India orders routinely run for several years before finality. Fix. Fund a dedicated appellate bench for competition matters with statutory disposal timelines.

    Conclusion

    The reluctance of cash-rich Indian firms to invest is being read as a political economy problem rather than a demand or global uncertainty problem. Concentrated political power, an uneven playing field and the fear of being displaced by a national champion together deny new entrants confidence in a 10 to 20 year horizon. Reversing that requires dispersing economic power, which carries political costs the current settlement has no incentive to accept. What remains unresolved is whether market concentration will be treated as a cost to growth or retained as a political asset.

    Industrial Policy and Private Investment in India

    1. What industrial policy does: It is the set of state interventions that shape which industries expand, through licensing, tariffs, incentives, public investment and ownership rules.
    2. The arc since Independence: The Industrial Policy Resolutions of 1948 and 1956 built a mixed economy with reserved public sector schedules, the licensing regime of the 1960s and 1970s restricted private entry, and the New Industrial Policy of 1991 abolished licensing for most sectors.
    3. India’s scale: Manufacturing contributes around 17 per cent of Gross Domestic Product against a 25 per cent target, and India accounts for about 2.8 per cent of global manufacturing output against China’s roughly 29 per cent.
    4. The current gap: Weak domestic private capital formation persists even as foreign investment rises, with cumulative Foreign Direct Investment crossing about $1.14 trillion between April 2000 and December 2025.

    Laws Governing Industry and Competition in India

    1. Industries (Development and Regulation) Act, 1951: The parent law for central regulation of scheduled industries, and the statutory basis of the industrial licensing regime.
    2. Monopolies and Restrictive Trade Practices Act, 1969: Regulated large business houses through asset thresholds to prevent economic concentration, and was repealed after those thresholds were removed post-1991.
    3. Competition Act, 2002: Replaced the 1969 Act, prohibits anti-competitive agreements and abuse of dominance, and establishes the Competition Commission of India to regulate combinations.
    4. Competition (Amendment) Act, 2023: Introduces a deal value threshold for merger review, a settlement and commitment framework, and shorter approval timelines.

    Government Initiatives for Industry and Investment

    1. Make in India (2014): Aims to raise manufacturing’s share of Gross Domestic Product towards 25 per cent, largely through ease of doing business measures.
    2. Production Linked Incentive scheme (2020): Covers 14 sunrise and strategic sectors with outcome-linked financial incentives paid on incremental output.
    3. National Manufacturing Mission: Announced in the 2025-26 Budget, targeting a 25 per cent Gross Domestic Product share and 143 million jobs by 2035, with a focus on solar photovoltaics, electric vehicle batteries, green hydrogen and wind.
    4. National Single Window System: Consolidates central and state clearances into a single application interface for investors.
    5. Invest India: The dedicated investment facilitation agency created after the Foreign Investment Promotion Board was abolished in 2017.

    Challenges in Industrial Policy and Private Investment

    1. Logistics and infrastructure costs: Power, transport and cluster gaps raise the operating cost of a new plant and lengthen its payback period. Eg. Logistics costs remain close to 8 per cent of Gross Domestic Product. Fix. Front-load the National Infrastructure Pipeline in states with the weakest evacuation and port connectivity.
    2. Land acquisition risk: Title complexity and local resistance delay projects long enough to destroy their business case. Eg. The POSCO steel project in Odisha was shelved after prolonged land disputes. Fix. Build titled and pre-cleared land banks with plug-and-play utilities before inviting investment.
    3. Tariff and trade shocks: External trade measures can remove an export market after capacity has been built for it. Eg. The 50 per cent United States tariff imposed in August 2025 hit roughly 55 per cent of India’s United States-bound exports. Fix. Diversify market access through trade agreements and deepen participation in global value chains.
    4. Workforce readiness for Industry 4.0: Adopting automation and artificial intelligence systems requires reskilling at a scale current training capacity cannot deliver. Eg. Only about 4.7 per cent of India’s workforce has formal skill training, against roughly 96 per cent in South Korea. Fix. Fund employer-led reskilling through the re-skilling fund created under the Industrial Relations Code, 2020.
    5. Import dependence in strategic inputs: Heavy reliance on imported electronics, semiconductors and pharmaceutical inputs exposes downstream manufacturers to supply shocks. Eg. Electronics assembly in India depends on imported display and chip components. Fix. Extend performance-linked incentives to component and materials manufacture rather than final assembly alone.

    Matching Previous Year Question

    “[2025, GS3, 15 marks] Discuss the rationale of the Production Linked Incentive (PLI) scheme. What are its achievements? In what way can the functioning and outcomes of the scheme be improved?”

  • What young want, and why creating good jobs is no longer optional

    Why in the News

    Almost 70 per cent of urban job seekers surveyed in Delhi said they were looking for a job that would place them on their ideal career path from the start, instead of settling for any job. The survey covered over 3,000 randomly sampled men and women, 24 years of age on average, living in middle-class residential areas of the capital, and was conducted in the summer of 2023. Their stated career goal was predominantly salaried or formal-sector employment. The Periodic Labour Force Survey (PLFS) for the same year records an urban labour market that cannot supply that goal, with less than 50 per cent of the urban workforce in salaried jobs. A follow-up experiment then exposed a random subset of the same job seekers to real-world job openings and salaries, and re-surveyed them a year later. Correcting their information lowered their expectations and left their aspirations untouched, so the contest is over who adjusts, the young or the labour market.

    What is the Periodic Labour Force Survey (PLFS)?

    1. Purpose: The PLFS is the official household survey that estimates how many people are working, seeking work or outside the labour force, and in what kind of work they are engaged.
    2. Nodal body: The National Sample Survey Office under the Ministry of Statistics and Programme Implementation conducts it and is the principal source of employment estimates in India.
    3. Activity status measures: Usual Status classifies a person by activity over the preceding 365 days, while Current Weekly Status treats a person as unemployed if they did not work even one hour in the reference week.

    What do young urban job seekers actually want from work?

    1. A career path, not a job: Almost 70 per cent said they wanted an opening that put them on their ideal career path from the start rather than any available job, and more men said this than women.
    2. Formal salaried work is the goal: The stated career goal was predominantly salaried or formal-sector employment rather than casual or own-account work.
    3. Women lean harder towards salaried jobs: More women job seekers aspired to salaried positions than men did.
    4. Only 14 per cent of women prefer self-employment: Just 14 per cent of the women interviewed said they would rather work for themselves.
    5. A third of men want to run enterprises: More than a third of the men wanted to start their own businesses.
    6. Public sector preference is a myth: A comparable share of these men and women were looking for private-sector salaried jobs, which cuts against the dominant narrative of a strong preference for government jobs.

    How far does the urban labour market fall short of those preferences?

    1. Salaried work is a minority outcome: Less than 50 per cent of India’s urban workforce holds a salaried job.
    2. It is scarcer still for the young: Merely one in every three employed 24-year-olds holds a salaried job, a lower share than for the workforce as a whole.
    3. Government jobs are a tenth of the market: No more than 10 per cent of the urban workforce is in the public sector or government jobs.
    4. The formal private sector is barely larger: Only about 15 per cent of the urban workforce is in the formal private sector.
    5. Self-employment is the largest single category: Of those working, 40 per cent are self-employed.
    6. Most self-employment is subsistence, not enterprise: An overwhelming majority of these businesses hire no worker at all and report an annual turnover of less than Rs 10 lakh, so the aspiration to build a firm meets a market of one-person shops.

    Why do salary expectations diverge from what these jobs actually pay?

    1. The occupations tested: Respondents were asked what they expected to earn as an accounts keeper, a primary school teacher, a data entry operator, a hospital attendant and an electrician, and each expectation was measured against actual PLFS earnings for the same occupation.
    2. Expectations run up to 40 per cent above reality: Job seekers expect up to 40 per cent higher salary than the earnings the PLFS records for the same work.
    3. Men are the more over-optimistic: Male job seekers expect almost Rs 8,000 more per month than the actual average earnings for these jobs.
    4. The gap widens for salaried work: For salaried jobs specifically, male job seekers expect Rs 8,500 more per month than actual earnings.
    5. The aggregate divergence exceeds 30 per cent: Taken together, salary expectations sit more than 30 per cent above reality, and the skew is sharper still among job seekers below 25 years of age, especially young men.
    6. Information and inexperience explain the gap: A lack of information or outright misinformation about openings and pay, combined with inexperience of the job market, are the two obvious sources of the misalignment.

    What did correcting job seekers’ information change, and what did it leave untouched?

    1. The design: A random subset of the 3,000 job seekers was informed about real-world job opportunities and salaries, and both the informed and the non-informed groups were re-surveyed twelve months later.
    2. Expectations fell: Accurate information significantly dampened labour-market expectations of landing the ideal job, relative to those who were not informed.
    3. Men disengaged first: Men in particular became less likely to report that they were on their ideal career path.
    4. Search effort fell with belief: That disillusionment was accompanied by a decline in men’s job-search intensity.
    5. The two exits from a failed search: As preferred job offers fail to materialise, job seekers adjust expectations downwards and either remain in the same jobs or leave the labour market and enrol at educational institutions.
    6. Aspirations did not move: The answer on whether aspirations changed is a clear no, since these men and women continued to aim for formal-sector jobs or dynamic entrepreneurship a year later, because aspirations are long-term goals and not easily malleable.
    7. High education costs make the expectation rational: Good-quality education is increasingly bought from private institutions at rising cost, so a high expected salary is not only aspirational but necessary to recover that outlay.

    Challenges to the Periodic Labour Force Survey

    1. Informal work is under-captured: Household surveys do not fully record home-based, gig and platform work in a workforce that is about 90 per cent informal. Eg. Delivery and ride-hailing riders working across two aggregators are frequently recorded as ordinary self-employed workers. Fix. Align the activity definitions with International Labour Organization and System of National Accounts practice so multi-job holders, freelancers and platform workers are counted separately.
    2. No skill mapping against job requirements: The survey does not match worker skills to the requirements of available jobs, so structural unemployment cannot be measured from it. Eg. The India Skills Report finding that only about half of graduates are employable has no counterpart in official survey data. Fix. Add a skills and job-requirement module so mismatch is measured rather than inferred.
    3. Rural data has been low frequency: Rural estimates were historically produced only once a year, so rural distress is visible with a long lag. Eg. A monsoon failure that pushes workers back into farm labour shows up only in the following annual round. Fix. Extend high-frequency quarterly or monthly rounds to rural areas rather than confining them to towns.
    4. Urban bias in the high-frequency rounds: The quarterly bulletins have been confined to urban areas, which under-measures the larger rural workforce. Eg. Quarterly urban unemployment rates are debated publicly while comparable rural numbers are unavailable. Fix. Publish a single integrated quarterly series covering both sectors on the same reference period.
    5. New job categories are missing: Gig, digital, start-up and green jobs are not adequately represented in the occupational classification the survey uses. Eg. Solar installation and battery recycling roles have no distinct occupational code. Fix. Integrate Employees’ Provident Fund Organisation, National Career Service and PLFS records so emerging job creation is tracked from administrative data as well.

    Conclusion

    Young urban job seekers want formal salaried careers and dynamic enterprise, and correcting their information about the market lowers what they expect to earn without changing what they want. That asymmetry places the burden of adjustment on the economy rather than on the young, and realising these aspirations requires a structural transformation that creates jobs with regular pay and benefits. The four Labour Codes are a step in that direction, and creating good jobs and genuine career paths, rather than jobs alone, is no longer optional. Failure carries a specific cost, which is the squandered potential of an entire generation.

    Employment and Unemployment in India

    1. What is measured: An unemployed person is of working age, that is 15 years and above, without work, currently available for work and actively seeking it in a reference period.
    2. Structure of the workforce: The Labour Force Participation Rate stood at 59.3 per cent in 2025, about 90 per cent of the workforce is informal, and nearly 58 per cent of salaried workers still lack a written contract.
    3. The absorption problem: Services drive most output growth but employ under 30 per cent of the workforce, while manufacturing contributes only about 16 to 18 per cent of Gross Domestic Product against roughly 26 per cent in China.
    4. Types of unemployment tested: Frictional, structural, cyclical, seasonal, disguised, voluntary and chronic unemployment are distinguished, with disguised unemployment concentrated in agriculture where marginal productivity approaches zero.

    Laws and Rules Governing Employment in India

    1. Code on Wages, 2019: Consolidates four wage laws, sets a statutory floor wage, and extends minimum wage cover beyond the roughly 30 per cent of workers it earlier reached.
    2. Industrial Relations Code, 2020: Merges three laws, raises the closure and retrenchment approval threshold from 100 to 300 workers, and gives fixed-term workers parity and gratuity after one year.
    3. Code on Social Security, 2020: Merges nine laws, defines gig and platform workers for the first time, and requires aggregators to contribute 1 to 2 per cent of turnover to a welfare pool.
    4. Occupational Safety, Health and Working Conditions Code, 2020: Consolidates 13 laws into one licence, one registration and one return, and caps hours at 8 to 12 daily and 48 weekly.
    5. Commencement of the four Codes: All four came into force on 21 November 2025, replacing a fragmented body of central labour legislation.
    6. Mahatma Gandhi National Rural Employment Guarantee Act, 2005: Guarantees 100 days of wage employment per rural household in a financial year.

    Government Initiatives for Employment Generation

    1. PM Viksit Bharat Rozgar Yojana: An employment-linked incentive approved in July 2025 with a Rs 99,446 crore outlay, targeting 3.5 crore jobs over two years.
    2. e-Shram Portal: A national database issuing Universal Account Numbers to unorganised workers and integrating access to more than 14 central schemes.
    3. PM Internship Scheme: Launched in 2024 to offer 1 crore internships in top companies over five years.

    Challenges in Employment Generation in India

    1. Lopsided structural change: India moved from agriculture to services without a job-rich manufacturing phase, so the sector that absorbs low-skilled labour elsewhere never scaled here. Eg. Manufacturing’s share of output has been stuck near 17 per cent against a 25 per cent policy target. Fix. Direct incentives to textiles, leather, food processing and electronics assembly, which absorb low and semi-skilled workers at scale.
    2. Capital-intensive investment bias: Investment flows to information technology and infrastructure rather than to labour-intensive activity, so output growth outruns job growth. Eg. Under the Production Linked Incentive scheme, most disbursed incentive has gone to large scale electronics assembly and pharmaceuticals, both capital intensive lines. Fix. Weight incentive schemes by jobs created per rupee of assistance rather than by output alone.
    3. Firms stay small to avoid compliance: Threshold-linked obligations reward staying under the size limit, which caps productivity and formal hiring. Eg. Micro, small and medium enterprises face more than 1,450 annual compliances costing Rs 13 to 17 lakh. Fix. Extend the Jan Vishwas approach of decriminalising minor compliance offences, which already covered 183 provisions across 42 central Acts.
    4. Skill deficit at both ends: Only about 4.7 per cent of the workforce has formal skill training, against roughly 96 per cent in South Korea, so employers and applicants describe different jobs. Eg. The Annual Status of Education Report 2023 found a quarter of rural youth aged 14 to 18 unable to read a Class 2 text. Fix. Tie curricula to Industry 4.0 and green job roles through mandatory industry-academia apprenticeship linkages.
    5. Women are kept out of paid work: Caregiving, domestic duties and mobility barriers hold female participation far below male participation. Eg. Urban female Labour Force Participation Rate stood at 25.8 per cent against 75.6 per cent for men in 2024. Fix. Enforce creche provision and workplace safety obligations already carried in the Codes.

    Matching Previous Year Question

    “[2023, GS3, 15 marks] Most of the unemployment in India is structural in nature. Examine the methodology adopted to compute unemployment in the country and suggest improvements.”

  • [22nd May 2026] The Hindu OpED: Noise annoys: India must enforce noise pollution regulations uniformly and consistently

    [22nd May 2026] The Hindu OpED: Noise annoys: India must enforce noise pollution regulations uniformly and consistently

    Question (2020, GS2): “Judicial Legislation is antithetical to the doctrine of separation of powers as envisaged in the Indian Constitution. In this context justify the filing of large number of public interest petitions praying for issuing guidelines to executive authorities.
    Linkage: This question directly addresses the core tension of the Patna High Court case: whether courts issuing executive-style guidelines (like noise limits and enforcement mechanisms) violates the separation of powers, or if it is justified by the sheer volume of public interest petitions stemming from executive inaction.

    Mentor comment

    The Patna High Court issued Statewide directives on the emission of high-decibel noise through an order dated 14 August 2026. The order closes an escalation that began in Surendra Prasad vs State of Bihar. A February 2025 hearing before a single judge in that case acknowledged DJ trolleys and loudspeakers to be a major source of noise in Patna. The same hearing criticised the Bihar State Pollution Control Board (BSPCB) for failing to curb the problem. India already has comprehensive noise law, so the directives are not filling a gap in the rules. What is contested is whether a constitutional court that has taken on the functions of a regulator is a remedy or an admission that routine enforcement has collapsed.

    What are the Noise Pollution (Regulation and Control) Rules, 2000?

    1. Subordinate legislation under an environmental statute: The Rules were made under the Environment (Protection) Act, 1986, and noise is separately treated as an air pollutant under the Air (Prevention and Control of Pollution) Act, 1981 when present in harmful concentrations.
    2. Limits are set zone by zone and by time of day: The Rules fix permissible ambient limits across residential, commercial, industrial and silence zones, with a lower limit at night than by day. Residential areas must stay below 55 decibels by day and 45 decibels at night.
    3. Silence zones carry a stricter regime: Areas within 100 metres of hospitals, educational institutions and courts are silence zones, with tighter limits and restrictions on loudspeaker use.
    4. Loudspeakers are barred at night: Loudspeakers and public address systems may not be used between 10 p.m. and 6 a.m., with a limited festival relaxation that a State government may notify.

    What is a decibel?

    1. A logarithmic unit, not a linear one: The decibel scale compresses a very wide range of sound intensities, so a rise of 10 decibels is a tenfold increase in sound energy and is perceived as roughly a doubling of loudness.
    2. Standards are set as averages, not peaks: Ambient noise limits are expressed as day and night equivalent levels for a zone, which is why a single loud event can breach the limit for an entire area.

    How did a single city’s complaint become a Statewide order?

    1. The Board was told to produce the enforcement record: After criticising the BSPCB, the Court directed it to obtain reports from the police on permissions granted to operators of these noise sources and on the action taken against them.
    2. The record showed enforcement stopping at the town boundary: In October the police reported seizing equipment and levying fines over three months in Patna, Barh and Fatuha, and taking no action at all in Masaurhi.
    3. A nil return was treated as evidence of non-enforcement: The judge called the picture “unbelievable” for suggesting there were no noise violations in Masaurhi at all.
    4. The Court moved from records to persons: Police officers were summoned in the course of the hearings, and boilerplate affidavits filed in response were upbraided from the bench.
    5. The escalation ended in Statewide relief: The 14 August order extended what began as a Patna grievance into directives binding across Bihar.

    What did the Patna High Court direct?

    1. Enforcement must become routine, not complaint-driven: Authorities were directed to pursue enforcement on their own initiative rather than waiting for a member of the public to file a complaint against a specific source.
    2. Operators must register themselves: DJs, sound-system operators and event halls were directed to register with the subdivisional authorities, which converts an invisible population of operators into a listed one.
    3. The cut-off was moved forward by five minutes: Loudspeakers were directed to stop playing at 9.55 p.m., five minutes before the law’s 10 p.m. limit.
    4. The five minutes are a compliance device, not a concession: The margin gives operators time to wind up, and it removes the defence that carrying on past 10 p.m. is only a matter of a few minutes.

    Why does enforcement fail even where the law is comprehensive?

    1. The failure is in application, not in drafting: Comprehensive rules have existed since 2000, and the Court’s intervention illustrates how dismal enforcement has become despite them.
    2. Complaint-based enforcement puts the cost on the victim: It is absurd to expect the public to complain about every DJ or horn before the police can respond, and a complainant in a small town faces the operator socially afterwards.
    3. Governments have an incentive to tolerate the violation: Loud events belong to constituents, and antagonising them carries a political cost that enforcement carries no matching reward for.
    4. Responsibility is split between two agencies: The pollution control board owns the standards and the police own the power to seize and prosecute, so neither is accountable for the outcome when the other does nothing.
    5. Episodic action has hardened into the norm: Drives launched around a festival and abandoned afterwards teach operators that the rule applies for a fortnight in the year.

    Does uniform noise enforcement collide with the right to practise culture?

    1. The sources are ordinary social occasions: Loud noise is produced by festivals, weddings, political campaigns and religious events, not mainly by industry, so every enforcement action touches a social gathering.
    2. Enforcement therefore reads as interference: Rules create friction with people who believe they have a right to practise their culture as they deem fit, which is what makes the state reluctant to act.
    3. The competing right is also constitutional: Courts have repeatedly held that people have a right under Article 21 to be protected from unlawful noise, so the question is between two claimed rights and not between culture and convenience.
    4. The claim has already been decided: A Supreme Court ruling of 2005 held that noise pollution violates Article 21 and that the use of loudspeakers, even for religious purposes, is not a fundamental right.

    Is a High Court acting as a regulator a solution or a symptom?

    1. The Court is doing the executive’s work: With episodic enforcement having become endemic, the Patna High Court becoming a quasi-regulator is creditable as a stopgap measure.
    2. A stopgap is not a regulatory system: A court supervises through hearings and contempt, which is an expensive and slow substitute for routine administrative enforcement by a subdivisional officer.
    3. Court-driven compliance decays when the case ends: Enforcement sustained by a listed matter tends to lapse once the bench changes or the petition is disposed of.
    4. The right test is behavioural, not judicial: The success of the order should be measured by whether the State develops a consistent habit of enforcement, not by the number of directions issued.

    Challenges to enforcing the Noise Pollution Rules, 2000

    1. Penalties are too small to deter: Fines under the general environmental penalty provisions are trivial against the earnings of a single wedding or campaign engagement, so paying is cheaper than complying. Eg. Equipment seizures rather than fines were what the Bihar police reported as their main action. Fix. Move to graded penalties linked to the event’s scale and to cancellation of the operator’s registration on a second breach.
    2. Traffic noise sits outside the permission system: The largest single urban source is road transport, and horns and modified silencers are not covered by any event permission or registration regime. Eg. Metros such as Delhi and Mumbai routinely breach the 55 decibel residential daytime limit. Fix. Enforce horn and silencer standards through automated noise cameras at signalised junctions, linked to the vehicle registration database.
    3. Silence zones are breached where enforcement matters most: Hospitals, schools and courts sit on arterial roads where the 100 metre silence zone cannot be maintained without traffic management. Eg. Silence zone signage exists around most large hospitals without any accompanying restriction on the road. Fix. Require every notified silence zone to carry a traffic calming plan approved along with the zone notification.
    4. Festival relaxations become the operating rule: States may permit loudspeaker use beyond the night limit on a small number of days a year, and the exemption expands informally into the surrounding weeks. Eg. Enforcement drives are routinely suspended for the length of a festival season rather than for the notified days. Fix. Publish the notified relaxation dates in advance and require a written order for any extension, subject to review.
    5. The register has no custodian system: The subdivisional offices directed to hold the operator register have no software, no dedicated staff and no publication duty attached to it. Eg. The nil action return from Masaurhi shows what an unmonitored subdivision produces. Fix. Host the operator register online at State level with each permission and each violation recorded against the operator’s entry.
    6. Data does not exist to prove a breach: Prosecution needs a calibrated measurement at the time and place of the offence, and most police stations have no sound level meter. Eg. Real-time ambient noise monitoring covers only a handful of Indian cities. Fix. Equip every police station in a notified urban area with a calibrated meter and make the reading an admissible enforcement record.

    Conclusion

    India’s noise problem is a failure of routine enforcement rather than a gap in law, and the Patna High Court has had to supply the enforcement architecture the executive did not, through mandatory registration, self-initiated policing and a wind-up margin before the statutory cut-off. Court supervision is a legitimate stopgap and it is not a regulatory system. The order will have worked only if the State keeps registering operators and acting on violations after the case is no longer listed. Consistency, not the number of directions, is the measure.

    Noise Pollution in India

    1. About: Noise pollution is excessive, unwanted or harmful sound that disrupts the environment and harms human health, arising from traffic, industry, construction, loud music and public events beyond permissible levels.
    2. Health burden: Chronic exposure raises hypertension, heart disease and stroke risk, and workplace noise alone causes around 500,000 hearing loss cases globally each year.
    3. Wider effects: Noise impairs children’s learning and drives stress, anxiety and depression, and it disrupts animal communication and breeding. Eg. Marine traffic noise disorients whales and dolphins that depend on echolocation.
    4. Policy standing: The United Nations Environment Programme declared noise an emerging environmental threat in 2022, and the European Environment Agency now ranks it among the top three environmental health risks behind only air pollution and temperature.

    Laws and Rules Governing Noise Pollution

    1. Air (Prevention and Control of Pollution) Act, 1981: Includes noise within the definition of an air pollutant where it is present in concentrations harmful to humans, animals, plants, property or the environment, and industrial noise is regulated by State Pollution Control Boards under it.
    2. Environment (Protection) Rules, 1986: Prescribe source-specific noise standards for motor vehicles, air conditioners, refrigerators, diesel generators and construction equipment.
    3. Motor Vehicles Act, 1988 and rules made under it: Prohibit multi-toned and shrill horns and the removal or alteration of a silencer, and provide the basis for vehicle noise limits at the point of type approval.
    4. Bharatiya Nyaya Sanhita, 2023: Retains public nuisance as an offence. Police most often invoke that provision against a loudspeaker operator in the absence of a measured reading.

    Key Facts about Noise Standards

    1. World Health Organization (WHO) Environmental Noise Guidelines, 2018: Recommend 45 decibels by day and 40 decibels at night for road traffic noise, values stricter than India’s residential limits.
    2. European burden estimate: Transport noise causes an estimated 66,000 premature deaths a year in Europe, along with 50,000 new cardiovascular cases and 22,000 type-2 diabetes cases.
    3. Scale of exposure: Over 20 per cent of Europeans, more than 110 million people, face harmful transport noise, with 4.6 million reporting severe sleep disturbance.
    4. Firecracker limit in India: The Central Pollution Control Board caps firecracker noise at 125 decibels measured at 4 metres from the point of bursting.

    Back2Basics: State Pollution Control Boards

    1. Statutory basis: Constituted by State governments under the Water (Prevention and Control of Pollution) Act, 1974, and given further functions under the Air (Prevention and Control of Pollution) Act, 1981.
    2. Composition: A chairman with knowledge of environmental protection, officials nominated by the State government, representatives of local authorities, and representatives of companies and corporations.
    3. Core power: Grant, refuse or withdraw consent to establish and consent to operate for any industry discharging effluent or emitting pollutants, which is the licence an industry cannot run without.
    4. Relationship with the Centre: The Central Pollution Control Board lays down standards, coordinates the boards and resolves disputes between them, and may direct a State board on any matter.
  • Climate resilience starts with the health workforce

    Why in the News

    Floods in Kerala and Assam have exposed the challenge of protecting lives during climate-related disasters, with attention going to rescue, relief camps and rebuilding. Analysis of climate-health governance across South and Southeast Asia shows that the workforce which prevents a disaster from becoming a prolonged public-health crisis is trained through fragmented, donor-supported projects rather than through the health system's own institutions.

    What is a climate-resilient health system?

    1. About: A climate-resilient health system is one able to anticipate, respond to, cope with and recover from climate-related shocks without interrupting routine health services.
    2. What it rests on: Its resilience ultimately depends on the workforce that delivers adaptation, since surveillance, emergency response and community outreach are performed by people rather than by plans.
    3. What changes under climate stress: Many of the foundational competencies required for climate adaptation already exist within health systems, and what changes is the context in which they must operate.
    4. The design principle: Climate change requires reorienting existing competencies through a climate lens and introducing new competencies where needed, rather than replacing what already exists.

    What is a heat action plan?

    1. About: A heat action plan is a city or region specific preparedness protocol that sets temperature thresholds, colour-coded warnings, and assigned responsibilities for health facilities, municipal bodies and emergency services during a heatwave.
    2. Why it is health-led: It converts a meteorological forecast into concrete health system action, covering hospital surge beds, oral rehydration supply, cooling spaces and outreach to outdoor workers and the elderly.

    What does the health workforce actually do during a climate disaster?

    1. Hospital preparedness: Hospitals prepare for medical emergencies, which is the visible clinical face of the response.
    2. Disease surveillance: Surveillance teams monitor disease outbreaks, since displacement and standing water raise the risk of communicable disease after a flood.
    3. Water quality testing: Laboratories test water quality, which determines whether relief camps and returning households face contamination risk.
    4. Community outreach: Community health workers reach vulnerable households, carrying care to those who cannot reach a facility.
    5. Cross-department coordination: Public health officials coordinate responses across departments, since the response involves disaster management, water supply, municipal services and health together.
    6. The net effect: It is the health workforce that prevents a natural disaster from becoming a prolonged public-health crisis, which is the least visible part of the response.

    What have states already put in place?

    1. Surveillance: States have begun to strengthen surveillance systems, which is the first line of detection for post-disaster outbreaks.
    2. Heat action plans: States have developed region-specific and city-specific heat action plans.
    3. Emergency preparedness: States have improved emergency preparedness arrangements within the health system.
    4. Programme integration: States have begun integrating climate considerations into several public-health programmes rather than treating climate as a separate vertical.
    5. The illustrative case: Kerala's response to the floods illustrates how health departments are increasingly incorporating public-health measures into disaster response.

    What does the South and Southeast Asia evidence show?

    1. The regional scope: The analysis covers climate-health governance across South and Southeast Asia, so the finding is regional rather than confined to one country.
    2. The central finding: Workforce development across the region remains fragmented, with no common architecture linking training to the health system's own institutions.
    3. The funding pattern: Climate-health training is largely confined to donor-supported or project-supported initiatives.
    4. What that implies: Capability rises and falls with the funding cycle of individual projects rather than accumulating within the system.
    5. Why the region matters for India: India's own state-level heat action plans and surveillance strengthening sit inside this regional pattern, so the fragmentation finding applies directly to Indian districts.

    Why does workforce capacity remain a surge response rather than a standing capability?

    1. The three questions the record raises: Whether these capacities can be sustained across all states, districts and levels of the health system; how surge capacities can be developed given the severe shortage of health workers across India; and whether capacities are being embedded across the workforce or continue to depend on individual relief-specific programmes and emergency mobilisation.
    2. The competency position: The competencies needed are largely present already, so the deficit is not one of knowledge.
    3. The institutional position: Those competencies sit in isolated training programmes rather than in the systems that produce, supervise and evaluate health workers.
    4. The consequence: Capacity is activated only during emergencies rather than translated into routine practice.
    5. The shortage constraint: The severe shortage of health workers across India limits how much surge capacity can be raised from an already stretched base.

    What would institutionalising climate-health competencies require?

    1. Beyond isolated training: Building climate-resilient health systems requires moving beyond isolated training programmes towards institutionalising climate-health competencies.
    2. The five integration points: These competencies should be integrated into pre-service education, professional development, supportive supervision, planning, and performance management.
    3. Pre-service education first: Placing climate-health content in pre-service education means every entrant carries the competency, rather than only those a project reaches.
    4. Supervision and performance: Embedding competencies in supportive supervision and performance management is what converts a completed training into observed practice.
    5. The three enablers: The integration must be supported by sustained governance, financing and institutional mechanisms.

    Challenges to Building a Climate-Resilient Health Workforce

    1. Absolute workforce shortage: Surge capacity cannot be drawn from a base that is already below norm, since redeploying staff for a flood response leaves routine services uncovered. Eg. Rural health facilities across India carry large shortfalls of specialists against Indian Public Health Standards, and community health centres report specialist vacancies in the range of two-thirds of sanctioned posts.
    2. Donor-cycle training: Competencies built through project funding disappear when the project closes, so the same district is trained repeatedly. Eg. Climate-health training across South and Southeast Asia remains largely confined to donor-supported or project-supported initiatives.
    3. Absence from pre-service curricula: Medical, nursing and allied health curricula do not carry climate-health competencies, so every entrant needs retrofitting. Eg. Heat illness protocols and post-flood outbreak management reach practitioners through workshops rather than through undergraduate training.
    4. Frontline worker load: Community health workers already carry multiple programme responsibilities, so a climate role is added without relief elsewhere. Eg. Accredited Social Health Activists deliver maternal health, immunisation, non-communicable disease screening and survey duties on an incentive-based payment structure.
    5. Data and early warning gaps: Health surveillance and meteorological forecasting run on separate systems, so an alert does not automatically reach a health facility. Eg. Heat action plans depend on India Meteorological Department warnings reaching district health officers in time for hospital preparation.
    6. Financing for adaptation: Adaptation finance for health competes with mitigation and infrastructure, so recurring workforce costs go unfunded. Eg. Global adaptation finance fell from 28 billion dollars to 26 billion dollars between 2022 and 2023, against a commitment to double it to 40 billion dollars by 2025.
    7. Attrition and contractual staffing: Much of the trained emergency workforce is on contract, so trained staff leave and the competency leaves with them. Eg. National Health Mission staff are engaged on contract across most States, with recurring demands for regularisation.

    Conclusion

    The health workforce is what prevents a climate disaster from becoming a prolonged public-health crisis, and its competencies are already largely present within health systems. The deficit is institutional, since climate-health training across South and Southeast Asia sits in donor-funded and project-funded initiatives rather than in pre-service education, professional development, supportive supervision, planning and performance management. Embedding those five points, supported by sustained governance, financing and institutional mechanisms, is what converts emergency mobilisation into routine practice. Until that happens, every flood and heatwave will draw on a surge capacity that has to be assembled afresh.

    Climate Change and Health in India

    1. The exposure: India faces heatwaves, floods, cyclones, droughts and air pollution simultaneously, so climate acts on health through multiple pathways rather than one.
    2. Heat: Rising heat exposure raises heat stroke, cardiovascular and renal illness, and reduces outdoor labour productivity, with outdoor workers, the elderly and pregnant women most exposed.
    3. Vector-borne disease: Warming and altered rainfall shift the range and season of malaria, dengue, chikungunya and Japanese encephalitis, moving transmission into districts and altitudes previously unaffected.
    4. Water-borne disease: Floods and cyclones contaminate drinking water and trigger diarrhoeal disease, cholera and leptospirosis outbreaks in the weeks after the event.
    5. Air quality: Ambient and household air pollution contribute to a very large share of India's non-communicable disease burden, with respiratory and cardiac mortality concentrated in the Indo-Gangetic Plain during winter.
    6. Nutrition: Crop yield loss and price shocks from extreme weather transmit into dietary quality, which shows up as child undernutrition rather than as a disaster statistic.
    7. The institutional response: The National Programme on Climate Change and Human Health, launched in 2019 under the National Health Mission, is the nodal programme, with State and district climate-health cells and nodal officers.
    8. The global frame: The Global Goal on Adaptation under the Paris Agreement now carries the 59 Belem Adaptation Indicators, the first global indicators for adaptation, spanning water, food, health, ecosystems, infrastructure and livelihoods.

    Government Initiatives

    1. National Action Plan on Climate Change: The 2008 framework of national missions, whose State Action Plans on Climate Change carry the health adaptation components at State level.
    2. National Action Plan for Heat Related Illnesses: Issued by the health ministry, it prescribes surveillance of heat-related illness and death, hospital preparedness, and health advisories during the heat season.
    3. National Disaster Management Authority heat guidelines: Guidelines for preparation of heat action plans, first issued in 2016 and revised subsequently, which States and cities use to build local plans.
    4. Ayushman Arogya Mandirs: Health and wellness centres delivering comprehensive primary health care, which are the delivery point for climate-sensitive surveillance and outreach at the community level.
    5. Integrated Disease Surveillance Programme and Integrated Health Information Platform: The national outbreak detection system, which is the mechanism through which post-flood and post-cyclone outbreaks are identified.
    6. Mission LiFE: A behavioural initiative on sustainable consumption, positioned as the demand-side counterpart to institutional climate action.

    Key Facts about Climate and Health Governance

    1. World Health Day: Observed on 7 April, marking the founding of the World Health Organization in 1948.
    2. National Doctors' Day: Observed on 1 July in India.
    3. Declaration on Climate and Health: COP28 at Dubai in 2023 was the first Conference of the Parties to formally address the health impacts of climate change, with a Declaration on Climate and Health endorsed by more than 140 nations, calling for climate-resilient health systems, extreme heat protocols and health co-benefits of mitigation. India did not sign it.
    4. Health Day at COP: COP28 also hosted the first dedicated Health Day on the official Conference of the Parties agenda, convened by the Presidency and the World Health Organization.
    5. Belem Adaptation Indicators: The 59 Belem Adaptation Indicators adopted at COP30 are the first global indicators for the Global Goal on Adaptation, and health is one of the domains they cover.
    6. Baku Adaptation Road Map: A two-year structured agenda running from 2026 to 2028 under the global goal on adaptation work programme, guiding progress on the Belem indicators and adaptation finance tracking.
    7. Adaptation finance goal: COP30 signalled a tripling of adaptation funding to 120 billion dollars a year by 2035 within the wider 1.3 trillion dollar pact, as a political signal rather than a binding commitment.

    Challenges in Climate and Health Governance

    1. Split institutional mandates: Climate policy sits with the environment ministry, disaster response with disaster management authorities and delivery with health departments, so no single authority owns climate-health outcomes. Eg. Heat action plans are issued under disaster management guidelines, and heat illness surveillance runs through the health ministry.
    2. Plans without financing: State and city plans are prepared without a dedicated budget line, so implementation depends on reallocating funds from other heads. Eg. Reviews of Indian heat action plans have found most lack identified funding sources and legal backing.
    3. Weak local vulnerability data: Plans use uniform thresholds rather than locally derived ones, so warnings misfire in humid or high-altitude districts. Eg. Heat thresholds calibrated for dry inland cities do not capture the combined temperature and humidity stress in coastal districts.
    4. Under-recording of climate-attributable deaths: Heat and flood-related mortality is recorded under proximate clinical causes, which understates the burden used to justify funding. Eg. Heat stroke deaths are frequently certified as cardiac or renal failure without the heat exposure being recorded.
    5. Primary care infrastructure gaps: Facilities lack cooling, uninterrupted power and water security, which are prerequisites for functioning during a heatwave or a flood. Eg. Many primary health centres operate without assured power backup for cold chain and emergency care.
    6. Fragmented surveillance integration: Meteorological, water quality and disease surveillance systems do not exchange data automatically, so early warning does not translate into facility-level preparation. Eg. Outbreak detection after floods relies on manual reporting through the Integrated Disease Surveillance Programme.
    7. International finance shortfall: Adaptation finance for the health sector remains a small fraction of climate finance, which pushes workforce costs back onto domestic budgets. Eg. Adaptation finance globally fell from 28 billion dollars to 26 billion dollars between 2022 and 2023.

    Way Forward

    1. Put climate-health in pre-service curricula: Introduce climate-health competencies into medical, nursing, allied health and public health curricula, so every new entrant carries them without retrofitting.
    2. Embed competencies in supervision and appraisal: Add climate-health tasks to supportive supervision checklists and to the annual performance appraisal of district health officers and facility staff.
    3. Fund workforce costs from domestic budgets: Provide a recurring National Health Mission budget line for climate-health cells, district nodal officers and refresher training, so capability does not lapse with donor projects.
    4. Localise heat and flood thresholds: Derive district-specific temperature, humidity and rainfall thresholds from local mortality and morbidity data, rather than applying uniform national cut-offs.
    5. Integrate the data systems: Link India Meteorological Department warnings, water quality testing and the Integrated Disease Surveillance Programme, so an alert automatically triggers facility-level preparation.
    6. Improve cause-of-death recording: Add climate exposure fields to death certification for heat, flood and cyclone events, so the burden is measured and can be budgeted against.
    7. Climate-proof health facilities: Provide assured power backup, cooling, water security and structural resilience at primary health centres and community health centres in high-exposure districts.
    8. Regularise the emergency workforce: Convert contract emergency and surveillance staff into regular cadres, so trained capacity remains in the system rather than leaving with the contract.

    Matching Previous Year Question

    “[2024, GS2, 15] In a crucial domain like the public healthcare system, the Indian State should play a vital role to contain the adverse impact of marketisation of the system. Suggest some measures through which the State can enhance the reach of public healthcare at the grassroots level.”

  • The Vanashakti verdict is balanced and pragmatic

    Why in the News

    The Supreme Court of India delivered its judgment in Vanashakti vs Union of India on 29 July 2026, on the fate of projects that began construction or operation without obtaining prior Environmental Clearance (EC). The ruling shuts the executive routes to regularisation while holding that the statutory power to create a fresh one survives, which moves the question of legacy violations from administrative discretion to statutory law making.

    What is prior Environmental Clearance under the Environment Impact Assessment Notification, 2006?

    1. The requirement: Prior Environmental Clearance is the approval a project proponent must obtain before commencing construction or operation of a listed project, based on an assessment of the project's likely environmental consequences.
    2. The legal source: It is mandated by the Environment Impact Assessment Notification, 2006. That notification is issued under Section 3 of the Environment (Protection) Act, 1986, the provision empowering the central government to take measures to protect and improve environmental quality.
    3. Coverage: It applies to listed sectors including mining, thermal power, infrastructure, construction and building projects above notified thresholds, and to real estate developments above specified built up area.
    4. Why the word prior matters: The clearance is a precondition for starting work, so an approval granted after work has begun cannot perform the function the law assigns it, which is to shape the project before its impact occurs.

    What is an ex post facto environmental clearance?

    1. Definition: An ex post facto environmental clearance is an approval granted to a project that has already commenced construction or operation without clearance, regularising the completed activity after the fact.

    What is an Office Memorandum in environmental regulation?

    1. Definition: An Office Memorandum is an internal executive communication issued by a ministry to set out an administrative procedure, and it carries no independent statutory force of its own.
    2. Its limit: It cannot create an exception to a requirement imposed by a statutory notification, since an administrative instrument cannot override the instrument that ranks above it.

    What did the Supreme Court hold on the 2017 Notification and the 2021 Standard Operating Procedure?

    1. Prior clearance reaffirmed as mandatory: The Court firmly reiterated that obtaining prior Environmental Clearance is a mandatory legal requirement under the Environment Impact Assessment Notification, 2006.
    2. The 2017 window is closed: Project proponents who commenced construction or operations without prior clearance and did not apply under the earlier violation mechanisms cannot now seek regularisation under the 2017 Notification.
    3. The 2021 Standard Operating Procedure struck down: The 2021 Standard Operating Procedure, issued as an Office Memorandum, was held legally unsustainable because an administrative memorandum cannot override the requirement of prior clearance.
    4. No fresh applications: Both mechanisms are no longer available for fresh cases, so the immediate operative message to project developers, industries and infrastructure agencies is that no fresh application can be made under them.
    5. What survives: The central government retains its Section 3 power to frame a fresh statutory mechanism for violation cases, if it considers this necessary in the larger public interest.

    Why did so many projects proceed without prior environmental clearance?

    1. Regulatory uncertainty: Some projects proceeded because the applicable regime was unsettled at the time work began, and the proponent could not identify with certainty which approval its category required.
    2. Incorrect interpretation of the law: Others proceeded on a mistaken reading of the requirement, treating a clearance as inapplicable to their category or their scale of activity.
    3. Failure to obtain approvals: A third set simply failed to obtain the necessary approvals before commencement, without any question of ambiguity in the law.

    Why does the distinction between an administrative memorandum and a statutory notification decide the outcome?

    1. Source of authority: A statutory notification draws its force directly from Section 3. An Office Memorandum draws only on the executive's power to instruct its own officials.
    2. Capacity to modify a legal requirement: Only an instrument of equal statutory standing can qualify a requirement imposed by the Environment Impact Assessment Notification, 2006, which is why the 2021 memorandum failed and a fresh notification would not.
    3. Procedural discipline: A statutory notification must be published, is open to legislative and judicial scrutiny in the form it takes, and cannot be varied by an internal circular.
    4. The practical consequence: The Court has not foreclosed relief for legacy violations, it has relocated the power to grant that relief from the ministry's administrative desk to a formal statutory instrument.
    5. A limit on the executive's own convenience: The distinction removes the option of granting case by case relief through evolving internal procedure, which is the mechanism through which the earlier windows expanded.

    Does barring post facto regularisation protect the environment or only strand completed projects?

    1. The deterrence claim: Environmental law cannot encourage deliberate violations by allowing routine post facto approvals, since a proponent who knows regularisation is available has no reason to wait for clearance.
    2. The proportionality claim: Indiscriminate closure or demolition of every violation project does not necessarily serve environmental protection or the larger public interest, particularly where the project is otherwise environmentally acceptable.
    3. The sunk investment problem: Numerous industrial units, commercial developments, infrastructure projects and public utility projects across India are in violation, and substantial investments have already been made in them.
    4. The pathway vacuum: Many such projects never applied under the earlier violation windows, so the closure of the 2017 scheme and the striking down of the 2021 memorandum leaves them with no legal pathway at all.
    5. How the judgment resolves the tension: It preserves the mandatory character of prior clearance while acknowledging the practical reality, refusing to convert the acknowledgement into a direction that the government must act.

    What safeguards must any future one time regularisation scheme carry?

    1. No permanent amnesty: Any future scheme cannot become a permanent violate first and regularise later mechanism, which is the specific design failure the Court guarded against.
    2. Strictly one time: The opportunity must be one time and confined to specified categories of violation projects, rather than a standing window that renews itself.
    3. Statutory authority: It must be issued as a notification under Section 3 and not as an administrative memorandum.
    4. Environmental damage assessment: The scheme must require an assessment of the environmental damage that the unauthorised commencement has already caused.
    5. Remediation and compensation: It must attach remediation measures and environmental compensation to the assessed damage, so that regularisation carries a cost proportionate to the harm.
    6. Strict compliance conditions: It must impose strict compliance conditions on the regularised project going forward, and be carefully designed within the framework of environmental law.
    7. No judicial direction to create it: The Court did not direct the central government to introduce such a scheme, it clarified that the government may do so if it considers it necessary in the larger public interest.

    Challenges to implementing the Vanashakti verdict

    1. Projects left without any pathway: Legacy violators outside the earlier windows now have no forum to approach until the government chooses to act, and inaction is a permissible outcome under the judgment. Eg. Real estate developments that exceeded their approved built up area before the 2017 window opened have no application route once the 2021 memorandum stands struck down.
    2. Capacity to assess environmental damage: Damage assessment for an already operating project requires baseline data that was never collected, because the baseline study is precisely what a prior clearance would have produced. Eg. State Pollution Control Boards in several States function with vacant technical posts and rely on proponent submitted monitoring data.
    3. Defining specified categories: Any future notification must draw a line between the proponent who acted in genuine regulatory uncertainty and the one who simply avoided approval, and the source material offers no test for that line. Eg. The 2017 Notification's six month window was criticised for treating a small unit's procedural lapse and a large mining expansion on identical terms.
    4. Fresh litigation risk: A one time notification will itself be challenged, so relief through this route is not quick relief. Eg. The 2021 Standard Operating Procedure survived for close to five years before it was set aside in the present judgment.
    5. Lender and contractual exposure: Projects with no clearance pathway carry impaired security for the banks that financed them, and the exposure does not sit with the proponent alone. Eg. Infrastructure projects halted for want of clearance have previously moved into stressed asset classification with their lending consortia.
    6. Enforcement against operating violators: Closure of the regularisation route does not by itself produce enforcement action, and the Court has not directed any. Eg. Show cause proceedings against units operating without clearance have historically ended in continued operation under interim orders.

    Conclusion

    The judgment settles that ex post facto regularisation cannot be granted by administrative memorandum while holding that Section 3 still permits a carefully framed statutory route. What it changes is the instrument, not the availability of relief, and it attaches damage assessment, remediation and compensation as the price of any such relief. What remains unresolved is whether the central government will exercise that power at all, since the Court has left the decision entirely to it. Until it does, thousands of legacy violation projects sit outside any legal pathway.

    Environmental Impact Assessment in India

    1. What it is: Environmental Impact Assessment is the process of predicting, evaluating and mitigating the environmental consequences of a proposed project before a decision on approval is taken.
    2. When it became mandatory: It was made legally mandatory in India by the Environment Impact Assessment Notification of 27 January 1994, which was superseded by the Environment Impact Assessment Notification, 2006.
    3. Project categorisation: Category A projects are appraised at the central level by the Union Ministry of Environment, Forest and Climate Change on the recommendation of an Expert Appraisal Committee, while Category B projects are appraised by the State Environment Impact Assessment Authority.
    4. The B1 and B2 split: Category B projects are further divided into B1, which require a full impact assessment report, and B2, which are exempted from that requirement.
    5. The four stages: The process runs through screening, scoping, public consultation and appraisal, with public consultation comprising a public hearing at the site and written responses from concerned persons.
    6. The 2020 draft: A draft Environment Impact Assessment Notification was published in 2020 for public comment and was never notified.

    Constitutional Framework Governing Environmental Protection

    1. Article 21: Guarantees the right to life, judicially read to include the right to a clean and healthy environment.
    2. Article 48A: Directs the State to protect and improve the environment and to safeguard the forests and wildlife of the country.
    3. Article 51A(g): Places a fundamental duty on every citizen to protect and improve the natural environment including forests, lakes, rivers and wildlife.
    4. Article 253: Empowers Parliament to legislate for the whole or part of India to implement international agreements, the provision under which the Environment (Protection) Act, 1986 was enacted.
    5. Seventh Schedule, Concurrent List Entry 17A: Places forests in the Concurrent List, moved there from the State List by the Forty second Constitutional Amendment.
    6. Seventh Schedule, Concurrent List Entry 17B: Places protection of wild animals and birds in the Concurrent List.

    Laws and Rules Governing Environmental Clearance

    1. Water (Prevention and Control of Pollution) Act, 1974: Establishes the Central and State Pollution Control Boards and requires consent to establish and consent to operate for discharging effluent.
    2. Amended by the Water (Prevention and Control of Pollution) Amendment Act, 2024, which replaced imprisonment with monetary penalties for several contraventions.
    3. Air (Prevention and Control of Pollution) Act, 1981: Empowers the Boards to declare air pollution control areas and to regulate emissions from industrial plants.
    4. Environment (Protection) Act, 1986: The umbrella statute empowering the central government to take all measures necessary to protect and improve the quality of the environment.
    5. Section 5 empowers the central government to issue directions including closure, prohibition or regulation of any industry.
    6. Environment (Protection) Rules, 1986: Prescribe emission and effluent standards and the procedure for issuing directions under the parent Act.
    7. Environment Impact Assessment Notification, 2006: Lists the projects requiring prior clearance and fixes the appraisal procedure and the authorities at each level.
    8. Forest (Conservation) Act, 1980: Requires prior approval of the central government for diversion of forest land to non forest use.
    9. Renamed the Van (Sanrakshan Evam Samvardhan) Adhiniyam, 1980 by the amendment of 2023, which introduced exemptions for specified categories of land.
    10. Coastal Regulation Zone Notification, 2019: Regulates construction and industrial activity in the coastal stretches and the intertidal zone.
    11. National Green Tribunal Act, 2010: Constitutes a specialised tribunal for effective and expeditious disposal of cases relating to environmental protection and enforcement of legal rights relating to environment.
    12. Public Liability Insurance Act, 1991: Requires owners handling hazardous substances to hold insurance for immediate relief to persons affected by accidents.

    Government Initiatives for Environmental Regulation

    1. PARIVESH portal: A single window online hub for submission, monitoring and management of environment, forest, wildlife and coastal regulation zone clearance proposals, upgraded to its second version in 2023.
    2. National Clean Air Programme: A time bound national framework launched in 2019 to reduce particulate matter concentrations in identified non attainment cities.
    3. Extended Producer Responsibility portals: Digital registration and credit trading platforms for plastic, battery, tyre and electronic waste producers under the respective waste management rules.
    4. Green Credit Programme: A market mechanism notified in 2023 that awards tradable credits for voluntary environmental actions such as plantation and water conservation.
    5. Mission LiFE: A behaviour focused initiative launched in 2022 to shift individual and community consumption patterns towards sustainable practice.
    6. National Adaptation Fund for Climate Change: A central fund supporting State level adaptation projects in vulnerable sectors and regions.

    Key Facts about Environmental Regulation in India

    1. World Environment Day: Observed on 5 June, marking the opening of the 1972 United Nations Conference on the Human Environment at Stockholm.
    2. National Pollution Control Day: Observed on 2 December in memory of those who died in the 1984 Bhopal gas disaster.
    3. A dedicated environment court: The establishment of the National Green Tribunal in 2010 made India the third country in the world, after Australia and New Zealand, to set up a specialised environmental court.
    4. Public hearing notice: The Environment Impact Assessment Notification, 2006 requires a minimum notice period of 30 days for the public hearing stage.
    5. Consultant accreditation: Impact assessment consultants are accredited through the National Accreditation Board for Education and Training under the Quality Council of India.
    6. Central Pollution Control Board: Constituted in 1974 under the Water Act, it functions as the technical apex body for pollution monitoring and standards.

    Challenges in Environmental Impact Assessment in India

    1. Proponent funded assessment: The impact assessment report is commissioned and paid for by the project proponent, which places the assessor in a client relationship with the party being assessed. Eg. Accreditation of consultants through the National Accreditation Board for Education and Training was introduced after assessment reports were found to carry copied ecological baseline chapters.
    2. Weak public consultation: Hearings are held at short notice, in venues distant from affected habitations and in a language the affected population does not read the documents in. Eg. Public hearings for coal block expansions in central India have been challenged before the National Green Tribunal on grounds of inadequate local language disclosure.
    3. Expanding exemption categories: Successive amendments have moved project categories out of the assessment requirement or into the B2 exempt class, shrinking the regime's coverage. Eg. Building and construction projects above notified built up area thresholds have repeatedly been shifted between assessment categories through amendment notifications.
    4. Absence of cumulative impact assessment: Each project is appraised in isolation, so the combined load of several projects on the same river basin or airshed is never assessed. Eg. Hydropower projects in the Himalayan river basins have been cleared individually without an assessment of the cumulative effect on downstream flow.
    5. Post clearance compliance monitoring: Half yearly compliance reports are self submitted by proponents and rarely verified through independent field inspection. Eg. Regional offices of the Union environment ministry cover several States each with a small inspection staff, which makes physical verification of every cleared project impossible.
    6. State appraisal authority capacity: State Environment Impact Assessment Authorities carry the bulk of the caseload with limited technical staff and periodic vacancies in their expert committees. Eg. Clearances issued by State authorities during periods when their expert appraisal committees stood unconstituted have been set aside by the National Green Tribunal.

    Back2Basics: Environment (Protection) Act, 1986

    1. Enactment context: It was enacted in the aftermath of the Bhopal gas disaster of December 1984, which exposed the absence of a general statute covering all forms of environmental harm.
    2. Constitutional basis: It was enacted under Article 253 to implement the decisions taken at the 1972 United Nations Conference on the Human Environment at Stockholm.
    3. Character: It is umbrella legislation, giving the central government general powers over environmental quality rather than regulating a single medium such as air or water.
    4. Commencement: It came into force on 19 November 1986.
    5. Definition of environment: The Act defines environment to include water, air and land and the interrelationship existing among and between them and human beings, other living creatures, plants, micro organisms and property.
    6. Penalty regime: Section 15 provided for imprisonment and fine for contravention, and was amended by the Jan Vishwas (Amendment of Provisions) Act, 2023 to substitute monetary penalties adjudicated by an appointed authority for several offences.
    7. Administering ministry: It is administered by the Ministry of Environment, Forest and Climate Change.

    Way Forward

    1. Frame the statutory notification with a hard sunset: Issue any one time mechanism as a notification under the parent Act with a fixed closing date written into the instrument itself, so it cannot be extended by circular.
    2. Define eligible categories by test, not by sector: Set an objective test distinguishing genuine regulatory uncertainty from avoidance, so that the scheme does not become a general amnesty by default.
    3. Make damage assessment independent: Require the environmental damage assessment for each applicant to be conducted by an accredited third party appointed by the regulator, not commissioned by the proponent.
    4. Link compensation to assessed harm: Calibrate environmental compensation to the damage assessed and the period of unauthorised operation, rather than to a flat percentage of project cost.
    5. Fund and staff the State authorities: Fill technical vacancies in State Environment Impact Assessment Authorities and Pollution Control Boards before loading them with damage assessment for legacy cases.
    6. Digitise post clearance compliance: Route compliance reporting through the PARIVESH platform with automated flagging and mandatory random field verification of a fixed share of cleared projects.
    7. Publish the pending violation inventory: Compile and publish a sector wise and State wise inventory of projects operating without clearance, so that any future scheme is designed against a known caseload.

    Matching Previous Year Question

    “[2020, GS3, 10] How does the draft Environment Impact Assessment (EIA) Notification, 2020 differ from the existing EIA Notification, 2006?”

  • Centre’s fiscal outlook faces geopolitical, revenue risks

    Question (2025, GS2): “Examine the evolving pattern of Centre-State financial relations in the context of planned development in India. How far have the recent reforms impacted the fiscal federalism in India?”
    Linkage: The Centre’s reliance on new cesses and duties to meet its budget goals, rather than expanding the core tax base itself, directly impacts fiscal federalism. Cesses and surcharges do not go into the divisible pool shared with states, altering Centre-State financial dynamics.

    Mentor comment

    Controller General of Accounts data show the Centre’s gross tax revenues growing only 3.7% in the first quarter of 2026-27, with Goods and Services Tax collections contracting and Union excise duties falling more than a fifth. The fiscal arithmetic is being held near its budgeted position by a larger nominal Gross Domestic Product denominator, by non-tax receipts led by the Reserve Bank of India dividend, and by new cesses and duties, rather than by the tax base itself.

    What is the divisible pool of central taxes?

    1. About: The divisible pool is that part of the Centre’s gross tax revenue which is shared with the States, arrived at after deducting collection costs, cesses and surcharges.
    2. The States’ share: The Sixteenth Finance Commission retained the share of States in the divisible pool of central taxes at 41%.
    3. From gross to net: The Centre’s net tax revenue is what remains after devolution, and a factor of 65% of gross tax revenue reflects the ratio of net to gross tax revenues in 2025-26 and in the 2026-27 Budget Estimates.
    4. Why cesses matter to it: A cess levied for a specified purpose sits outside the divisible pool, so the same rupee raised through a cess rather than a tax does not reach the States as devolution.

    What is tax buoyancy?

    1. About: Tax buoyancy measures how far tax revenue grows for each unit of growth in nominal Gross Domestic Product, capturing both the natural response of the tax base and the effect of policy changes.
    2. What zero buoyancy means: Personal income tax revenue growth in 2025-26 was only 0.037%, which implies a buoyancy of zero, so the tax raised nothing extra despite the economy expanding.

    What is the Implicit Price Deflator?

    1. About: The Implicit Price Deflator is the ratio of nominal to real Gross Domestic Product, and it captures the average price change across everything the economy produces rather than a fixed consumption basket.
    2. How it is used here: An Implicit Price Deflator based inflation of 5% to 5.5% is what converts an expected real growth of about 7% into nominal Gross Domestic Product growth of 12.5% to 13% in 2026-27.

    What is a cess?

    1. About: A cess is a levy imposed for a specified purpose, collected over and above the base tax, and its proceeds are meant to be applied only to that stated purpose.
    2. Its fiscal effect: Cess proceeds are not shareable with the States, so a shift from taxes to cesses reduces the shareable pool while leaving gross collections unchanged.

    Why did the Centre’s gross tax revenues grow only 3.7%?

    1. Two large taxes were rationalised: Personal income tax and Goods and Services Tax were both subjected to substantive modifications in 2025-26, with extensive rate rationalisation in both cases and a substantive rate reduction in the case of the Goods and Services Tax.
    2. The stated expectation: Those reforms were expected to entail an initial revenue sacrifice, with subsequent expansion of the tax base offsetting the loss over time.
    3. The carry-forward into this year: Personal income tax showed growth of 6.8% in the first quarter of 2026-27, and Goods and Services Tax revenues contracted 11%.
    4. The 2025-26 baseline: Goods and Services Tax revenue growth for the second half of 2025-26 was 4.67%, and personal income tax growth over the same year was effectively nil.
    5. The excise duty cut: As retail fuel prices rose on the West Asian crisis, the government reduced excise duties to ease the burden on consumers, and revenue from Union excise duties contracted 22.4% in the first quarter of 2026-27.

    What three remedial measures has the government taken?

    1. A new cess replacing a discontinued one: A Health Security and National Security Cess was introduced with effect from 1 February 2026, even as the Goods and Services Tax Compensation Cess was discontinued.
    2. A higher windfall tax on fuel exports: The windfall tax on exports of diesel, petrol and aviation turbine fuel was increased with effect from 3 August 2026.
    3. Higher import duties on precious metals: Import duty rates were raised on gold and silver bullion and on other specific precious metal articles, sweepings and clad metals.

    How does a higher nominal GDP change the fiscal picture?

    1. The budgeted assumption is being exceeded: The Budget assumed nominal Gross Domestic Product growth of 10.04%, well short of the growth now expected for the year.
    2. The consistency check: That deflator range is consistent with Consumer Price Index inflation at 3.9% and Wholesale Price Index inflation at 9.3% in the first quarter of 2026-27.
    3. The level, not the growth rate, is lower: On the 2022-23 base series, nominal Gross Domestic Product is estimated at Rs 391 lakh crore, below the budgeted level of Rs 393 lakh crore.
    4. The net effect on revenue: Taken together, estimated gross tax revenue would be realised or fall short by a small margin.

    What has happened to transfers to the States?

    1. A sharp contraction in the first quarter: Tax devolution to the States contracted 19.5% in the first quarter of 2026-27, with an expectation of higher assignment of central tax revenues in subsequent months.
    2. The shareable pool narrows at the margin: The introduction of the non-shareable Health Security and National Security Cess produces a marginal reduction in the shareable pool, though some part of its revenues may reach the States as grants outside the Finance Commission route.
    3. Finance Commission grants are budgeted lower: Based on the Sixteenth Finance Commission’s recommendation, Finance Commission grants for the States are budgeted to contract by Rs 23,556 crore in 2026-27.
    4. The devolution share itself is unchanged: The contraction is in the amounts flowing, not in the entitlement, since the States’ share in the divisible pool stays at 41%.

    What is holding the revenue account together?

    1. The central bank dividend: The Reserve Bank of India transferred dividends to the Centre in May 2026, so 77% of the budgeted dividends and profits for the full year were already covered in the first three months.
    2. Weight of non-tax revenue: The Centre’s non-tax revenues contributed 37% of its net revenue receipts in the first quarter of 2026-27.
    3. Other receipts on track: The budgeted amounts for non-tax and non-debt capital receipts are expected to be realised.
    4. Subsidy pressure on the other side: Major subsidies had to be increased 37.4% in the quarter because of the unexpected rise in global crude oil prices.
    5. Revenue expenditure held down: Growth in revenue expenditure was contained at 7.4% over the same quarter.
    6. Capital expenditure front-loaded: Capital expenditure grew 23.7% in the first quarter of 2026-27, against a contraction of 23.3% in the fourth quarter of 2025-26.
    7. The full-year subsidy overshoot: Extrapolating first-quarter subsidies to the year, realised subsidies are expected to exceed the budgeted amount by about Rs 50,000 crore.

    Where do the deficit numbers stand, and what could push them off track?

    1. First-quarter deficit position: The fiscal deficit accounted for 18.2% of the annual budgeted magnitude in the first quarter, and the corresponding share of the revenue deficit was 0.4%.
    2. Why the revenue account looks strong: The revenue account balance is held up mainly by the contribution of non-debt receipts, not by tax collections.
    3. The full-year estimates: Fiscal deficit calculated as the increment in debt is estimated at Rs 18.16 lakh crore, giving a fiscal deficit-to-Gross Domestic Product ratio of 4.6% on the new series, with the debt-to-Gross Domestic Product ratio at 55.8%.
    4. Three named slippage risks: A shortfall in tax revenues, an unbudgeted increase in revenue expenditure arising from additional subsidies, and a slightly higher external debt amid sustained pressure on the Indian rupee.
    5. The overriding risk: An escalation of the war in West Asia would deliver a major jolt to the economy and to central finances.
    6. The unwound measure: The reduction in excise duty on fuel must be restored at some suitable time, since it is a temporary relief carried at a permanent revenue cost.

    What challenges does the Centre’s fiscal consolidation path face?

    1. Rate rationalisation without base expansion: A tax cut delivers the revenue sacrifice immediately and the base expansion only over an uncertain horizon. Eg. Personal income tax delivered a buoyancy of zero in 2025-26, the year its rationalisation took effect.
    2. Subsidy exposure to imported energy prices: Subsidy outgo is set by global crude prices rather than by a domestic policy decision. Eg. Major subsidies rose 37.4% in the first quarter of 2026-27, putting the full year on course to overshoot its budgeted provision.
    3. Reliance on a single large non-tax transfer: A dividend from the central bank is a discretionary, year-specific receipt that cannot be assumed to repeat. Eg. 77% of the full year’s budgeted dividends and profits were covered in the first three months of 2026-27.
    4. Revenue relief that is politically hard to withdraw: An excise duty cut given when fuel prices rise is difficult to reverse when they fall. Eg. Union excise duties contracted 22.4% in the first quarter of 2026-27 following the cut.
    5. Deficit ratios improved by a denominator effect: A higher nominal Gross Domestic Product lowers the deficit ratio without any change in borrowing. Eg. Nominal growth running ahead of the budgeted 10.04% flatters the 4.6% fiscal deficit ratio.
    6. Interest burden crowding out capital spending: A debt-to-Gross Domestic Product ratio near 56% commits a large share of revenue receipts to interest before any programme is funded. Eg. Capital expenditure was front-loaded 23.7% in the first quarter after contracting 23.3% in the preceding quarter, a pattern that shifts rather than raises the annual total.
    7. Exchange rate pressure raising external liabilities: A weaker rupee raises the rupee cost of external debt service without any new borrowing. Eg. Sustained pressure on the rupee is named as one of the three sources of possible slippage from budgeted outcomes.

    Conclusion

    The Centre’s 2026-27 outcomes are likely to stay close to budgeted levels, and the reasons are a larger nominal Gross Domestic Product, front-loaded non-tax receipts and three new revenue measures, not a tax base that is delivering. Gross tax revenue growing at barely a third of the pace of nominal output is the number that has to change, since the rate rationalisations of 2025-26 were justified on the promise of base expansion that has not yet appeared. The immediate unresolved decisions are when the excise duty cut on fuel is restored and how far an escalation in West Asia pushes subsidies beyond the overshoot already projected.

    What is Fiscal Federalism?

    1. About: Fiscal federalism is the division of taxation powers, expenditure responsibilities and transfer arrangements between the Union and the States in a federal system.
    2. Rationale: Revenue-raising powers concentrate at the Centre because major tax bases are mobile, while expenditure responsibilities concentrate at the States because services are delivered locally. Transfers exist to close that gap.
    3. Vertical fiscal imbalance: The mismatch between the Union’s revenue capacity and the States’ expenditure responsibilities, addressed through devolution of a share of central taxes.
    4. Horizontal fiscal imbalance: The mismatch across States in revenue capacity and expenditure need, addressed through the Finance Commission’s distribution formula among States.
    5. Third tier imbalance: The mismatch between the functions devolved to panchayats and municipalities and the revenue sources available to them, addressed through State Finance Commissions and grants.
    6. The transfer instruments: Tax devolution from the divisible pool, Finance Commission grants, and centrally sponsored schemes with a matching State contribution.

    Key Concerns Regarding Fiscal Federalism

    1. Shrinking divisible pool through cesses and surcharges: Levies outside the divisible pool raise Union revenue without expanding what is shared, so the effective transfer falls below the headline share.
    2. Erosion of State taxation autonomy under the Goods and Services Tax: States surrendered independent rate-setting on most indirect taxes, and rate decisions now require a collective decision in a council.
    3. Weak third tier finances: Local bodies depend on transfers rather than own revenue, and State Finance Commissions are constituted irregularly in several States.
    4. Contested horizontal distribution criteria: Weighting population, income distance and demographic performance sets States that have controlled population growth against those with larger populations.
    5. Conditionality attached to central transfers: Centrally sponsored schemes tie State spending to Union priorities, reducing the discretion that devolution is meant to confer.
    6. Off-budget and contingent liabilities: Borrowing routed through State-owned entities and guarantees sits outside the headline deficit at both levels, obscuring the true fiscal position.

    Constitutional Framework Governing Union Finances

    1. Article 265: No tax shall be levied or collected except by authority of law.
    2. Article 266: Establishes the Consolidated Fund and the Public Account of India and of each State.
    3. Article 267: Provides for the Contingency Fund of India, placed at the disposal of the President for unforeseen expenditure.
    4. Article 112: Requires the annual financial statement of estimated receipts and expenditure to be laid before Parliament.
    5. Article 246 and the Seventh Schedule: Distribute legislative and taxation powers between the Union and the States through the Union, State and Concurrent Lists.
    6. Article 246A: Confers concurrent power on Parliament and State legislatures to make laws on the Goods and Services Tax.
    7. Article 269A: Provides for the levy and collection of the Goods and Services Tax on inter-State supply and its apportionment between the Union and the States.
    8. Article 270: Provides for the distribution of taxes levied and collected by the Union between the Union and the States, and excludes cesses and surcharges from that distribution.
    9. Article 271: Empowers Parliament to levy a surcharge on specified taxes for the purposes of the Union, the proceeds of which accrue wholly to the Union.
    10. Article 275: Provides for grants-in-aid from the Union to States in need of assistance.
    11. Article 279A: Provides for the constitution of the Goods and Services Tax Council.
    12. Article 280: Provides for the constitution of a Finance Commission every fifth year to recommend the distribution of taxes and the principles governing grants-in-aid.
    13. Article 282: Permits the Union or a State to make any grant for any public purpose, the provision under which centrally sponsored schemes are funded.
    14. Article 292 and Article 293: Govern borrowing by the Union and by the States, with State borrowing subject to Union consent where the State is indebted to the Union.
    15. Article 360: Provides for a proclamation of financial emergency.

    Laws Governing Government Budgeting in India

    1. Fiscal Responsibility and Budget Management Act, 2003: Requires the Centre to limit the fiscal deficit and to lay medium-term fiscal policy statements before Parliament.
    2. Amended in 2018 to shift the primary anchor from the revenue deficit to a debt-to-Gross Domestic Product target, with an escape clause for specified circumstances.
    3. Fiscal Responsibility and Budget Management Rules, 2004: Prescribe the form of the disclosure statements and the quarterly review requirement.
    4. Comptroller and Auditor General’s (Duties, Powers and Conditions of Service) Act, 1971: Provides the basis for audit of Union and State accounts and for the reports laid before the legislatures.
    5. State fiscal responsibility legislation: Every State has enacted its own fiscal responsibility law setting deficit and debt limits, complementing the Union statute.
    6. Appropriation and Finance Acts: The Appropriation Act authorises withdrawal from the Consolidated Fund, and the Finance Act gives effect to the taxation proposals for the year.

    Government Initiatives in Public Financial Management

    1. Public Financial Management System: An end-to-end platform tracking fund release and utilisation from the Union to the last implementing agency, reducing float in the system.
    2. Direct Benefit Transfer: Routes subsidy and benefit payments to bank accounts directly, cutting duplication and leakage in the transfer chain.
    3. Single Nodal Agency mechanism: Requires each centrally sponsored scheme in a State to operate through one designated account, so unspent balances are visible.
    4. Special Assistance to States for Capital Investment: Provides fifty-year interest free loans to States tied to capital expenditure and to specified reforms.
    5. National Monetisation Pipeline: Raises resources by leasing operating public assets while retaining ownership, supplementing tax revenue for capital spending.
    6. Goods and Services Tax Network: The common technology platform for registration, return filing and invoice matching that generates the data underlying indirect tax collections.

    Back2Basics: Sixteenth Finance Commission

    1. What it is: A constitutional body constituted under Article 280 to recommend the distribution of net tax proceeds between the Union and the States, the allocation among States, and the principles governing grants-in-aid.
    2. Constitution: Constituted in December 2023, chaired by a former Vice Chairman of NITI Aayog.
    3. Award period: Its recommendations cover the five years beginning 2026-27.
    4. Advisory Council: The Commission is assisted by an Advisory Council of economists and public finance specialists.
    5. Status of recommendations: Its report is laid before Parliament along with an explanatory memorandum on the action taken, and the recommendations are advisory rather than binding.
    6. Additional terms of reference: Beyond devolution, the Commission examines disaster management financing and the review of State fiscal positions.

    Challenges in India’s Public Finances

    1. A low tax-to-Gross Domestic Product ratio: India’s combined tax collection relative to output remains below that of comparable middle-income economies, which caps what can be spent without borrowing. Eg. Gross tax revenue in the first quarter of 2026-27 grew at less than a third of the nominal output growth expected for the year.
    2. Narrow direct tax base: A small share of the population files and pays income tax, so any rate change transmits through a thin base. Eg. Personal income tax raised no more in 2025-26 than in the year before, despite nominal output expanding through that year.
    3. Rigidity of committed expenditure: Interest, salaries, pensions and statutory transfers consume most revenue receipts before discretionary spending begins. Eg. The debt-to-Gross Domestic Product ratio is estimated at 55.8% for 2026-27.
    4. Exposure to imported commodity prices: Fuel and fertiliser subsidies move with global prices rather than with domestic policy. Eg. Major subsidies rose 37.4% in the first quarter of 2026-27 on the unexpected rise in global crude oil prices.
    5. Volatility of non-tax receipts: Dividends, disinvestment proceeds and spectrum receipts are lumpy and cannot be relied on across years. Eg. Non-tax revenues contributed 37% of net revenue receipts in the first quarter of 2026-27.
    6. State-level fiscal stress and guarantees: Contingent liabilities from State-owned distribution companies and guaranteed borrowings sit outside headline deficits. Eg. Tax devolution to the States contracted 19.5% in the first quarter, tightening State cash positions in the same period.
    7. Weak link between capital spending and outcomes: Front-loading capital expenditure raises the quarterly number without ensuring project completion. Eg. Capital expenditure grew 23.7% in the first quarter of 2026-27 after contracting 23.3% in the preceding quarter.

    Way Forward

    1. Restore the excise duty on fuel on a stated schedule: Announcing the timing in advance converts a politically difficult reversal into a pre-committed step, as the analysis itself recommends.
    2. Publish base expansion metrics alongside rate rationalisation: Reporting the change in the number of filers and in registered taxpayers would test the premise on which the 2025-26 rationalisation was justified.
    3. Cap the share of revenue raised through cesses and surcharges: A ceiling would stop the divisible pool narrowing through instruments that bypass Article 270.
    4. Insulate subsidy budgeting from a single price assumption: Building a price band and a contingency provision into the subsidy estimate would prevent an overshoot of this size appearing mid-year.
    5. Treat central bank dividends as a windfall, not a base receipt: Directing above-trend transfers to debt reduction rather than to recurring expenditure would stop a one-off receipt becoming a structural assumption.
    6. Smooth capital expenditure across quarters: Front-loading followed by contraction disrupts contractor payment cycles and project execution, so a steady release profile serves outcomes better than a strong first quarter.
    7. Bring off-budget and guaranteed borrowing into the disclosure statements: Consolidated reporting at both Union and State levels is the precondition for the debt path to mean what it states.

    “[2019, GS3, 10] The public expenditure management is a challenge to the Government of India in context of budget making during the post liberalization period. Clarify it.”